
Blogs
Thaumatin Market 2032: Beyond the 7.5% CAGR—Sweetener Shifts Reshaping Growth
By pmarketresearch, 2026-09-21
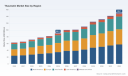
The Thaumatin Market: Strategic Trends and Commercial Opportunities Through 2032
The global thaumatin market has entered a phase of accelerating maturation, transitioning from a niche specialty ingredient to a strategically important component in the broader natural sweeteners and flavor modulation landscape. Valued at approximately $63.0 million in 2020, the market has expanded to $90.5 million by 2025, and forward projections indicate a trajectory toward $149.7 million by 2032. This expansion reflects a compound annual growth rate of 7.5 percent across the forecast period, a pace that signals sustained commercial momentum rather than a temporary cyclical upturn. The growth is not merely a function of volume expansion; it represents a structural shift in how manufacturers approach sugar reduction, flavor balancing, and clean-label formulation. Thaumatin's dual functionality as both a high-intensity sweetener and a taste-modifying agent positions it at the intersection of several converging demand forces, yet the market's evolution is shaped by constraints that require careful strategic navigation.
The current landscape is defined by a moderately concentrated competitive structure, with the top three players accounting for roughly 45 percent of combined revenue and the top five controlling just above half of the market. This concentration level suggests that while scale advantages exist, there remains meaningful room for specialized suppliers, regional distributors, and formulation-focused entrants to capture differentiated positions. The market's growth trajectory is not uniform across all segments; food-grade applications dominate the revenue mix, pharmaceutical-grade thaumatin commands a substantial secondary share, and a residual category supports niche industrial and specialty uses. Similarly, sweetening applications represent the largest end-use category, flavoring and taste-masking functions account for a significant portion, and a smaller share is distributed across auxiliary applications. These structural balances matter because they reveal where value creation is concentrated and where future margin opportunities are likely to emerge.
Market Dynamics and Structural Challenges
Despite the favorable growth outlook, the thaumatin market faces several interdependent challenges that will shape competitive outcomes over the next several years. The first and most fundamental constraint lies in raw material availability. Thaumatin is extracted from the katemfe fruit, which originates from a limited geographic base in West Africa. Total raw material exports from Ghana and Nigeria were approximately 210 metric tons in 2023, a volume that constrains the scale at which thaumatin can be produced and creates inherent supply elasticity limitations. This raw material bottleneck is not merely a logistical issue; it defines the ceiling for rapid volume expansion and makes supply chain resilience, farmer relationships, and extraction efficiency critical competitive variables. Companies that can secure stable katemfe access, optimize yield per ton of raw fruit, or develop blending strategies that reduce thaumatin intensity requirements will hold structural advantages in a supply-constrained environment.
A second challenge involves the tension between regulatory certainty and shifting nutritional labeling frameworks. Thaumatin benefits from a well-established regulatory foundation: it remains authorized as a sweetener and flavor enhancer in the European Union under Regulation (EC) No 1333/2008, and it is classified as generally recognized as safe by the FDA for use as a sweetener and flavor modifier in the United States. This regulatory clarity is a competitive asset that distinguishes thaumatin from newer or less-tested sweetener alternatives. However, regulatory approval alone does not guarantee commercial adoption. The European Commission's 2023 Nutri-Score algorithm, for instance, penalizes added sugars more heavily, which has accelerated reformulation efforts in beverages and cereal categories where thaumatin's role as a flavor enhancer and taste-balancing agent becomes commercially relevant. The challenge for manufacturers is that regulatory status and consumer perception do not always align; even authorized ingredients must navigate consumer skepticism around ultra-processed foods, label simplification expectations, and the broader clean-label movement that favors recognizable ingredient names.
A third structural challenge relates to cost and labor dynamics in the raw material supply chain. Small-scale farmers in West Africa handle cultivation and harvesting of the Thaumatococcus daniellii plant, and this labor-intensive model supports rural livelihoods but also introduces variability in yield quality, harvest timing, and supply consistency. Labor cost structures, weather variability, and the fragmented nature of smallholder cultivation can create fluctuations that ripple through extraction facilities and ultimately affect pricing stability for downstream customers. In a market where thaumatin already occupies a premium positioning relative to some bulk sweeteners, supply-side volatility can complicate long-term formulation commitments and contract negotiations. Addressing these constraints requires investment in farmer support programs, quality standardization initiatives, and potentially blended ingredient systems that reduce dependency on pure thaumatin volumes without sacrificing functional performance.
PW Consulting
Key Drivers Shaping the Market Trajectory
The market's expansion is being propelled by a combination of technological, regulatory, demand-side, and supply chain factors that reinforce one another. On the innovation front, formulation science has advanced significantly in using thaumatin not simply as a standalone sweetener but as part of blended systems designed to mitigate off-notes, enhance mouthfeel, and reduce the total sweetener load required to achieve target sensory profiles. Recent product launches illustrate this shift. In early 2025, Ingredion introduced a Reb M plus thaumatin blend developed for sugar-free yogurts, reporting a 38 percent reduction in aftertaste during European consumer trials. Around the same time, Natex UK Ltd launched the ThaumActive ready-to-use natural sweetener range tailored for flavored waters and protein beverages. These developments are meaningful because they demonstrate thaumatin's evolving commercial role: it is increasingly valued for its ability to improve the sensory quality of reduced-sugar and high-protein formats, rather than solely for its sweetness intensity.
Regulatory and policy dynamics provide another layer of momentum. The continued authorization of thaumatin across major markets gives formulators a predictable compliance pathway, which is especially valuable in categories such as beverages, dairy alternatives, and functional foods where ingredient scrutiny is high. At the same time, public health-oriented labeling and sugar taxation pressures are pushing manufacturers to reduce added sugar without sacrificing taste acceptance. Thaumatin's taste-modifying properties make it particularly useful in these reformulation scenarios, where it can soften bitterness from high-intensity sweeteners, improve the perceived sweetness profile at lower dosages, and support cleaner ingredient declarations when used in moderation. This regulatory and reformulation environment creates a durable demand pull, but it also favors suppliers who can offer technical support, application-specific guidance, and proven blend compatibility rather than bulk commodity pricing alone.
Consumer and enterprise behavior is shifting in ways that reinforce thaumatin's relevance. The broader sugar reduction trend is no longer confined to confectionery or soft drinks; it now extends to dairy, baked goods, RTD beverages, and sports nutrition formats. At the same time, the clean-label and natural ingredients movement favors plant-derived sweeteners with established regulatory histories over synthetic alternatives. Thaumatin's botanical origin and multi-functional profile align well with these preferences, particularly in premium and health-oriented product tiers where ingredient narrative matters. For large food and beverage manufacturers, thaumatin is increasingly evaluated not just on cost per unit of sweetness but on total formulation value, including taste modulation, label positioning, and compatibility with other natural ingredients.
Supply chain and cost structure changes are also reshaping competitive dynamics. Because katemfe supply is geographically concentrated and relatively limited, companies with integrated or closely coordinated sourcing arrangements are better positioned to manage price stability and supply continuity. At the same time, advancements in extraction efficiency, quality control, and downstream blending capabilities can improve the effective economics of thaumatin use. Suppliers that invest in application-focused formulation services, ready-to-use ingredient formats, and consistent batch quality can command stronger value capture even in a supply-limited environment. This dynamic is gradually rewarding capability-driven players over pure volume players, particularly as end-users seek to minimize formulation risk while navigating sugar reduction targets.
Competitive Landscape and Strategic Positioning
The competitive field features a mix of international ingredient companies, regional specialists, and distribution-focused suppliers. Tate & Lyle operates as a broad natural high-intensity sweetener producer, leveraging thaumatin within a wider portfolio that serves food and beverage applications. Its strategic advantage lies in scale, application breadth, and the ability to position thaumatin alongside complementary sweetening and texturizing ingredients. Naturex, now aligned with Givaudan, brings a natural ingredients and flavor expertise that supports thaumatin's use in taste-modulation contexts, especially where sensory balance and label-friendly positioning are priorities. Natex UK Ltd has carved out a specialist identity with a strong focus on natural thaumatin and formulated sweetening solutions, including its Sweetence brand, and its recent launch of ready-to-use formats for flavored waters and protein beverages reflects a deliberate move toward application-ready offerings that reduce customer formulation burden.
Van Wankum Ingredients and Silver Fern Chemical operate more on the supply and distribution side, connecting manufacturers with thaumatin supply for food and industrial applications, while Penta Manufacturing Company provides thaumatin as a natural sweetener and flavor enhancer with a U.S.-based commercial footprint. These companies illustrate a market where differentiation can come from multiple directions: portfolio breadth, technical formulation capability, regional supply reliability, or specialized customer segments. The presence of both established multinationals and focused specialists creates a competitive environment in which customer value is increasingly determined by service depth, application knowledge, and supply consistency rather than price alone.
The market structure is evolving along two parallel tracks. On one hand, there is consolidation pressure as larger ingredient groups seek to strengthen their natural sweetener portfolios and capture cross-selling opportunities across sweetening, flavor, and functional ingredients. On the other hand, there is room for fragmentation and specialization, particularly in application-tailored formats, regional market focus, and niche health-oriented categories. New entrants and smaller companies can compete by developing proprietary blends, securing reliable katemfe access through strong farmer relationships, or concentrating on underserved applications such as high-protein beverages, functional waters, or premium dairy alternatives. The strategic lesson is that thaumatin's market does not reward generic participation; it rewards companies that can link supply reliability with formulation utility and customer-specific technical support.
Forward Outlook: Trends and Commercial Implications
Over the next three to five years, several trends are likely to define thaumatin's commercial trajectory. The first is the growth of blended, application-specific sweetening systems. As formulators continue to balance taste, cost, label clarity, and sugar reduction goals, thaumatin's value will increasingly be expressed in combination with other natural sweeteners and flavor modulators. Ready-to-use blends and pre-balanced formulations will become more important because they reduce development time and sensory risk for customers, especially smaller manufacturers and private-label producers who may lack extensive in-house formulation resources. This trend favors suppliers that can offer standardized, application-tested formats with documented sensory outcomes.
The second trend is the widening of thaumatin's application footprint beyond traditional sweetener uses. Its function as a flavor enhancer and taste-masking agent is becoming more commercially visible in categories such as high-protein beverages, sugar-reduced dairy, and functional drinks where off-note suppression is critical. If this trajectory continues, thaumatin's revenue mix could gradually shift toward more value-added application contexts, where pricing power is supported by technical differentiation rather than commodity positioning. The opportunity here is substantial for companies that invest in sensory research, category-specific formulation guidance, and collaboration with customers during product development.
Saccharin Market
The third trend involves supply chain maturation and potential geographic diversification. Given the current concentration of katemfe exports from Ghana and Nigeria, any initiative that improves cultivation practices, expands responsible sourcing, or enhances extraction yield could meaningfully affect market capacity and price stability. At the same time, efforts to standardize raw material quality and strengthen farmer partnerships may reduce supply variability and improve long-term planning for downstream users. However, uncertainty remains. Crop sensitivity, climate conditions, and the social and economic complexity of smallholder supply chains mean that supply expansion cannot be taken for granted. Companies should treat raw material resilience as a strategic priority rather than an operational detail.
These trends create clear commercial opportunities, but they also carry risk. If sugar reduction momentum slows in certain categories, or if alternative sweeteners gain stronger consumer acceptance at lower cost points, thaumatin's growth rate could face headwinds. If regulatory frameworks evolve in ways that alter labeling expectations or ingredient disclosure norms, manufacturers may need to adapt formulation strategies quickly. And if supply chain disruptions affect katemfe availability, price volatility could test customer relationships and margin structures. The businesses best positioned to navigate these uncertainties will be those that build flexible sourcing, maintain strong technical credibility, and differentiate through formulation value rather than price competition alone.
Strategic Recommendations for Decision-Makers
For manufacturers and product developers, the priority is to treat thaumatin as a formulation enabler rather than a standalone sweetener. Integrating thaumatin into blended systems, investing in sensory validation early in the development cycle, and selecting suppliers with demonstrated application support can shorten time-to-market and improve taste outcomes in reduced-sugar formats. Companies should also evaluate ready-to-use and pre-blended options where they exist, especially for categories like flavored waters, protein beverages, and sugar-reduced dairy, where sensory balance is difficult to achieve with single-ingredient approaches.
For investors and strategic planners, thaumatin represents a market with steady structural growth and clear differentiation opportunities, but success depends on identifying players with credible supply relationships, formulation capabilities, and application-focused product architectures. Capital allocation and partnership decisions should weigh not only revenue trajectory but also raw material resilience, technical service depth, and the ability to capture value in higher-margin application segments. Companies that rely purely on commodity-style participation may face margin pressure, while those with specialty positioning and customer lock-in through formulation expertise are better placed to sustain value capture.
For procurement and supply chain leaders, securing predictable thaumatin supply requires a proactive approach. Long-term supplier relationships, quality consistency requirements, and contingency planning for raw material variability should be central to sourcing strategy. Where possible, procurement teams should collaborate with suppliers on traceable sourcing, batch standardization, and blended options that reduce exposure to pure thaumatin volume constraints. Building flexibility into specification and formulation parameters can also help mitigate the impact of supply fluctuations without compromising product quality or label commitments.
Understanding thaumatin's market trajectory at this level of detail is essential for companies making multi-year formulation, sourcing, and investment decisions. Broad growth figures provide useful context, but the real strategic value lies in segment-specific demand patterns, application-level performance data, regional sourcing dynamics, and competitor capability mapping. For decision-makers who need granular segmentation, scenario analysis, and customized recommendations tailored to specific product categories or markets, the complete PW Consulting research report offers a more detailed view of the data and strategic options that can inform next steps.
Thymol Market
For detailed analysis of this topic, please visit the official page: Thaumatin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Multiwall Paper Bags Market 2026: Why the 4.5% CAGR and $244.7M Outlook Changes Everything
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Multiwall Paper Bags Market
Navigating Transition: Market Overview and Key Challenges
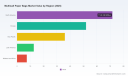
The multiwall paper bags market has established itself as a critical component of industrial packaging, serving sectors ranging from construction to agriculture. Over the past five years, the market has demonstrated steady expansion, with revenue climbing from approximately 135.4 million U.S. dollars in 2020 to an estimated 179.5 million in 2025. This trajectory reflects a compound annual growth rate of 4.5 percent, positioning the sector for continued moderate expansion through 2032, when revenues are projected to approach 244.7 million U.S. dollars. While the growth profile is stable rather than explosive, the underlying dynamics are shifting in ways that create meaningful strategic implications for manufacturers, investors, and procurement leaders.
The market structure remains relatively fragmented at the top, with the top three players collectively holding about 22.4 percent of revenue and the top five accounting for 28.7 percent. This concentration level indicates a landscape where scale advantages exist but do not fully dictate outcomes, leaving room for regional specialists and product-focused innovators to compete effectively. The distribution of revenue across regions shows North America as the largest contributor, followed by Europe and Asia Pacific, with Latin America and the Middle East and Africa representing smaller but growing shares. Across product types, kraft paper continues to anchor the market, while coated and recycled variants occupy meaningful niches. On the application side, building materials represent the largest end-use segment, with agriculture, chemicals, food, and minerals following in varying degrees of demand intensity.
Despite the constructive growth baseline, the industry is confronting several transition points that will shape competitive outcomes over the next five years. First, volatile raw material costs are compressing margins and forcing manufacturers to rethink procurement strategies and pricing models. Second, regulatory frameworks are accelerating the shift away from plastic-heavy multilayer sacks toward fully recyclable paper-based solutions, raising compliance costs but also opening differentiation opportunities. Third, demand patterns are evolving as end-users prioritize sustainability credentials, moisture resistance, and supply chain reliability, pushing suppliers to balance performance with environmental claims. These challenges are not merely headwinds; they are re-shaping the criteria by which companies win or lose in the market.
Key Drivers Reshaping the Landscape
Regulatory and compliance pressures are among the most consequential forces currently influencing the market. The EU Packaging and Packaging Waste Regulation, which begins applying from August 2026, requires improved recyclability documentation and labeling compliance for packaging, including multiwall paper bags. By 2030, all packaging must be recyclable, a mandate that favors sack kraft paper over multilayer sacks with high plastic content in multiwall applications. In parallel, plastic bag bans in various regions are compelling manufacturers to pivot toward sustainable, recyclable, and biodegradable materials as compliant alternatives. These regulatory shifts are raising the bar for product design and documentation, but they also reward suppliers that can demonstrate credible recyclability and reduced plastic use.
Raw material dynamics are equally central to the market's evolution. Benchmark kraft linerboard prices surged by 22 percent year-on-year in 2023 due to constrained supply and high energy costs, and volatility has persisted into subsequent periods. Fluctuating prices for paper and adhesives continue to challenge manufacturers, as rising input costs directly impact production economics and profit margins. This environment favors companies with vertically integrated production, diversified sourcing, and the ability to pass through cost adjustments without eroding customer relationships. It also incentivizes material efficiency innovations that reduce weight or improve strength-per-unit, helping to offset cost pressure while meeting performance requirements.
Kraft Paper Bag Market
Demand-side behavior is shifting in ways that reward performance and sustainability simultaneously. End-users in building materials, agriculture, chemicals, and food sectors are increasingly scrutinizing packaging for moisture resistance, durability, and environmental impact. For humidity-sensitive products, the ability to maintain integrity without relying on plastic layers has become a competitive differentiator. At the same time, procurement teams are seeking suppliers that can provide consistent quality, flexible sizing, and transparent sustainability credentials. These expectations are pushing manufacturers to invest in product development that addresses both functional and regulatory demands, rather than treating sustainability as a separate initiative.
Technology and process innovation are beginning to play a more visible role in competitive positioning. While multiwall paper bags may appear to be a mature product category, advances in production optimization, material formulation, and design intelligence are enabling suppliers to improve strength, reduce weight, and enhance moisture barriers. Recent product-level activity illustrates this direction: in May 2025, Mondi Group launched its re/cycle PaperPlus Bag Advanced, a high-performance paper bag designed for humidity-sensitive products with up to 60 percent reduced plastic use and a strong moisture barrier. This launch underscores how sustainability and performance are converging, setting a benchmark that other players will need to match or differentiate around.
Competitive Positioning and the Evolution of Market Structure
The competitive landscape features a mix of global packaging leaders and specialized manufacturers, each pursuing distinct positioning strategies. Mondi Group, headquartered in Vienna, focuses on AI-powered multiwall bag production, sustainable paper-based packaging, and moisture-resistant bag solutions for industrial applications including cement and chemicals. Its emphasis on humidity-sensitive performance and reduced plastic use aligns closely with regulatory and demand trends. Smurfit Kappa, based in Atlanta, specializes in AI-enhanced bag design, lightweight yet durable multiwall sacks, and eco-friendly industrial packaging, positioning itself around design intelligence and sustainability. Segezha Group, headquartered in Moscow, provides AI-assisted high-strength multiwall bags, biodegradable packaging solutions, and customizable industrial paper sacks for food and agricultural sectors, leveraging customization and biodegradability as differentiators.
WestRock Company, also headquartered in Atlanta, focuses on AI-driven material optimization, high-barrier multiwall bags, and recyclable paper bag technologies for building materials, chemicals, and agriculture sectors, emphasizing barrier performance and recyclability. Sonoco Products Company and International Paper contribute from the U.S. with broad industrial and consumer packaging portfolios, with International Paper supplying kraft paper bags and corrugated packaging for industrial and consumer applications. More regionally focused players add further diversity: Bag Supply Company manufactures millions of high-quality multiwall paper bags annually for agricultural, industrial, construction, and consumer goods; Southern Packaging LP supplies customizable multi-wall paper packaging solutions through vertically integrated production facilities for industrial bulk packaging; JohnPac produces cost-effective multiwall paper bags for seed and grain storage and transport with custom shapes and sizes; and Novolex offers its Dubl Life line of FSC-certified or 100 percent recycled kraft paper bags for industrial and consumer use.
PW Consulting
The strategic logic across these players reveals several differentiation paths. One is performance-led, targeting moisture resistance, strength, and barrier properties for demanding applications. Another is sustainability-led, emphasizing reduced plastic use, recyclability, biodegradability, and certified fiber sources. A third is cost and customization-led, serving specific end-use verticals with tailored sizes and economical production. Vertical integration and sourcing flexibility are recurring advantages in a volatile raw material environment, while investments in design and production intelligence are increasingly used to improve efficiency and product consistency.
Industry events and community engagement are also shaping the competitive rhythm. The PSSMA 2026 Production Managers' Seminar and Bag Boot Camp in Greenville, South Carolina, along with the PSSMA 2026 Annual Meeting in Napa, California, reflect ongoing지식交流 and capability-building within the sector. These gatherings provide forums for sharing operational best practices and aligning on emerging standards, which can accelerate adoption of improved processes and compliance practices across the supply base.
Looking at market structure evolution, the current fragmentation at the top suggests room for selective consolidation among regional players seeking scale, while also leaving space for differentiated specialists to thrive. New entrants are unlikely to disrupt the market through volume alone; instead, they will need to bring clear advantages in sustainability credentials, moisture performance, customization, or cost efficiency. The interplay between regulatory deadlines, raw material volatility, and end-user expectations will likely reward companies that can combine operational resilience with credible product innovation.
Forward Outlook: Trends Shaping the Next Three to Five Years
The first major trend is the acceleration of recyclable and reduced-plastic multiwall paper bag designs as regulatory and customer expectations converge. With the EU requiring all packaging to be recyclable by 2030 and plastic bag bans expanding in various regions, suppliers that can deliver high-performance paper-based sacks with minimal or no plastic content will gain a structural advantage. This trend creates opportunities for product differentiation tied to documented recyclability, reduced plastic use, and moisture barrier performance that does not rely on multilayer plastic construction. The commercial implication is clear: sustainability is becoming a performance attribute, not just a compliance checkbox.
The second trend is continued raw material cost volatility paired with a growing emphasis on material efficiency and supply chain resilience. As kraft linerboard and adhesive prices remain sensitive to supply constraints and energy costs, manufacturers will increasingly value sourcing flexibility, vertical integration, and design choices that improve strength-to-weight ratios. Companies that can maintain quality while optimizing material usage will be better positioned to protect margins and offer competitive pricing. Procurement leaders should expect more variability in lead times and input costs, making supplier reliability and transparency increasingly valuable.
The third trend is the gradual integration of production and design intelligence into multiwall bag manufacturing. While not a wholesale transformation of the category, AI-assisted design and material optimization are enabling suppliers to improve consistency, reduce waste, and tailor bags to specific end-use requirements. This trend supports both cost efficiency and product performance, and it may become a baseline expectation for leading suppliers over the forecast period. The opportunity lies in pairing these capabilities with clear customer benefits, such as customized sizing, enhanced moisture resistance, or faster response to specification changes.
Tea Bag Paper Market
Potential risks and uncertainties should not be overlooked. Regulatory timelines may shift or be implemented with varying rigor across jurisdictions, creating compliance complexity for suppliers operating in multiple markets. Raw material price swings could intensify if energy costs or supply disruptions escalate, pressuring margins even for well-prepared manufacturers. End-user demand could also evolve in unexpected ways if alternative packaging materials gain traction in specific applications, or if economic conditions slow procurement in construction and agriculture. Navigating these uncertainties will require scenario planning, flexible sourcing, and product portfolios that can adapt to changing requirements without sacrificing core performance.
Implications and Actionable Considerations for Decision Makers
For manufacturers, the priority is to align product development with the converging demands of recyclability, moisture performance, and cost efficiency. Investing in reduced-plastic or fully recyclable multiwall designs, improving material utilization, and strengthening sourcing flexibility can help protect margins while meeting regulatory and customer expectations. Building documentation and labeling capabilities that support compliance in key markets, particularly where recyclability requirements are tightening, will also reduce execution risk. Where possible, enhancing production and design intelligence can improve consistency and responsiveness, giving suppliers an edge in customized or performance-sensitive segments.
For investors, the market offers moderate growth with meaningful differentiation potential rather than uniform upside. Attention should focus on players with credible sustainability credentials, resilient cost structures, and clear positioning in performance-sensitive applications such as building materials, chemicals, and humidity-sensitive food or agricultural products. Vertical integration, diversified sourcing, and evidence of product innovation that reduces plastic content or improves barrier performance are useful indicators of competitive strength. At the same time, raw material volatility and regulatory complexity warrant careful assessment of margin resilience and compliance readiness across geographies.
For procurement and supply chain leaders, the emphasis should be on supplier capability and transparency rather than price alone. Evaluating suppliers on moisture resistance, recyclability documentation, customization flexibility, and sourcing stability can reduce risk in demanding applications. Given ongoing input cost variability, diversifying the supplier base where feasible and securing commitments that balance cost with reliability can improve outcomes. Engaging suppliers early on specification changes and compliance requirements can also smooth transitions as regulatory deadlines approach and performance expectations rise.
Strategic decisions in this market benefit from detailed, up-to-date intelligence on segment-level demand patterns, regional dynamics, and competitor movements. PW Consulting's comprehensive research report on the Multiwall Paper Bags Market provides deeper segmentation data, regional breakdowns, and customized guidance to support planning and investment choices. Accessing that level of detail can help translate the trends and considerations outlined here into precise, actionable strategies tailored to specific business contexts.
For detailed analysis of this topic, please visit the official page: Multiwall Paper Bags Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Manned Security Services Market: The 7.12% CAGR Signals a Strategic Shift
By pmarketresearch, 2026-09-21
The Manned Security Services Market: Strategic Trends and Commercial Opportunities in an Evolving Landscape
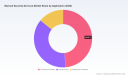
The manned security services market has reached a critical inflection point. In 2025, the sector crossed the $242.5 million threshold in annual revenue, building on a steady recovery from the $185.3 million baseline observed at the start of the decade. Over the past five years, the trajectory has reflected not just post-pandemic normalization, but a fundamental recalibration of how organizations think about physical protection. The market is projected to expand at a compound annual growth rate of 7.12 percent through 2032, reaching an estimated $393.1 million by the end of the forecast period. This growth is not merely an extension of historical patterns; it is being shaped by structural shifts in technology, regulation, labor dynamics, and buyer expectations. For executives, investors, and procurement leaders, understanding where value is being created—and where it is being eroded—requires looking beyond top-line numbers and examining the forces that will determine competitive advantage in the years ahead.
Market Snapshot and Core Challenges
A Sector in Transition
The market has grown consistently from 2020 through 2025, but the composition of that growth tells a more nuanced story. Commercial facilities continue to anchor demand, while industrial sites and residential complexes represent secondary but strategically important demand pools. The service mix remains dominated by traditional guarding, though cash and valuables protection and specialized security services contribute distinct, higher-margin segments that reflect evolving risk profiles. This diversification is a response to the reality that one-size-fits-all security models no longer satisfy the operational complexity of modern facilities, logistics networks, and public-facing institutions.
Challenge One: Labor Scarcity and Wage Pressure
The most persistent constraint on the industry is human capital. Manned security remains, by definition, labor-intensive. Organizations that rely on guard presence at perimeter points, access control stations, and roaming patrols are competing for a workforce that is simultaneously in high demand across adjacent sectors such as logistics, facilities management, and hospitality. Wage escalation is no longer a temporary fluctuation; it is a structural cost input that compresses margins for providers that compete primarily on price. In markets where basic guarding is commoditized, the pressure is especially acute, with thousands of active security companies vying for the same talent pool. The result is a two-tier dynamic: providers that can attract, retain, and professionalize their personnel through career pathways, training, and competitive compensation are gaining share, while those locked into low-cost models face turnover, service inconsistency, and reputational risk.
Worldwide Site Safety Service Market
Challenge Two: Regulatory Friction and Compliance Complexity
Regulation is reshaping how manned security operates across jurisdictions. In some regions, foreign ownership restrictions are mandating local control and altering the competitive playing field for international operators. In others, procurement frameworks are introducing new clauses that affect how private security functions are structured and contracted, particularly in cross-border or government-adjacent environments. These dynamics do not simply add administrative overhead; they influence market entry strategy, partnership models, and the cost of scaling. Companies that treat compliance as a one-time onboarding exercise are exposed, whereas those that embed regulatory intelligence into their operating design can convert constraints into barriers that protect incumbent positions.
Challenge Three: The Technology Expectation Gap
Buyers increasingly expect that manned security will be augmented by technology—remote monitoring, video analytics, access control integration, and data-driven reporting. Yet the integration of these capabilities with human presence remains uneven. Some incumbents have built seamless hybrid offerings; others are stitching together point solutions that create operational friction. The expectation gap is widening the wedge between providers that can deliver coordinated, intelligence-led protection and those that offer body-only presence without situational awareness. For decision-makers, this creates a procurement challenge: how to ensure that the human element and the technological layer reinforce each other rather than operate in parallel silos.
Key Drivers Shaping the Market
Technology as a Force Multiplier, Not a Replacement
The most consequential driver of market evolution is the maturation of technology that amplifies the effectiveness of security personnel rather than displacing them. Remote guarding stations, analytics-enabled video feeds, and integrated alarm response platforms allow a smaller on-site footprint to achieve coverage that previously required a larger physical guard complement. This is particularly relevant for organizations managing multiple sites, variable-risk environments, or extended operating hours. The strategic implication is not simply cost reduction; it is the ability to redeploy personnel to higher-value tasks such as incident response, customer engagement, and specialized patrols. Where technology is deployed thoughtfully, it raises the baseline quality of service and creates differentiation in a market that has historically competed on headcount and price.
Policy and Regulatory Signals Redirecting Investment
Recent policy developments are acting as catalysts for reallocation. The closure of a significant government business unit by one of the largest global providers illustrates how portfolio choices are being shaped by shifting contract landscapes and regulatory considerations. Simultaneously, procurement frameworks that govern private security functions abroad are introducing clarity—and complexity—into how services are structured for international operations. These signals matter because they influence not only who wins contracts, but how services are designed, staffed, and audited. Providers that proactively align their operating models with emerging compliance expectations are better positioned to secure long-term public and quasi-public contracts, while those that lag face re-bid risks and margin compression.
Demand-Side Shifts: Risk Profiles Are Becoming More Granular
On the demand side, organizations are moving away from generic security packages toward solutions that reflect the specific risk profile of their facilities, supply chains, and reputational exposures. Commercial facilities are prioritizing customer experience and loss prevention within a single security function. Industrial sites are emphasizing perimeter integrity, access control, and rapid incident escalation. Residential complexes are balancing resident safety with privacy and community integration. This granularity is driving demand for specialized services and for guard personnel who are trained not only in presence and deterrence, but in de-escalation, observation, and communication. The buyers who are winning contracts are those that articulate a clear security mission and tie it to measurable outcomes, rather than treating security as a generic cost center.
Cost Structure Evolution and the Pursuit of Predictability
Cost structures are shifting as labor, insurance, technology, and compliance costs converge. Providers are responding by standardizing service tiers, incorporating technology-assisted monitoring to moderate labor intensity, and building clearer pricing models that improve predictability for clients. This evolution benefits both sides: organizations gain budgeting clarity and service consistency, while providers gain operational discipline and reduced churn. The market is increasingly rewarding business models that balance human presence with scalable infrastructure, because that balance delivers the reliability that risk-conscious buyers require.
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation
The market features several large, globally active providers whose strategies reveal how scale, footprint, and integration are being leveraged. Allied Universal operates across North America with a broad service portfolio spanning manned guarding, mobile patrols, risk consulting, and technology-enabled solutions, anchored by strong government and commercial contracts. Its positioning reflects the value of a large, diversified contract base and the ability to offer integrated services that span physical presence and advisory support. Securitas, headquartered in Sweden, operates in dozens of markets with a focus on on-site guarding, mobile guarding, remote guarding, and integrated solutions, emphasizing manned personnel services supported by technology. Its strategy underscores the importance of geographic breadth and the hybrid model of human presence combined with remote capabilities. Prosegur, based in Spain, specializes in manned guarding combined with alarms, logistics, and integrated security solutions across a wide country footprint, illustrating how logistics-adjacent security can create cross-selling opportunities and operational synergies. GardaWorld, headquartered in Canada, delivers manned security, cash logistics, and risk management with a strong presence in government and high-risk environments, highlighting the premium that specialized, high-assurance services can command. Paladin Security and InterCon Security, both with North American foundations, emphasize government and commercial guarding contracts, demonstrating that regional depth and relationship-driven account management remain viable paths to growth even as global players expand.
Recent Developments as Strategic Signals
Recent contract activity and recognition highlight how incumbents are reinforcing their positions. A major provider secured a new contract for guard services at county mental health facilities and clinics, a type of engagement that blends public-sector procurement with the need for trained, sensitive, and consistent personnel. Another provider ratified a renewed contract with a university that expanded protections and included wage increases, reflecting both the prioritization of campus safety and the willingness to invest in personnel to sustain service quality. Separately, a North American security provider received multiple industry awards, signaling that excellence in execution, client service, and operational discipline continues to be recognized and rewarded. These examples are consistent with a broader pattern: winning engagements often requires a combination of reputation, reliable staffing, and the ability to adapt services to the specific environment.
Market Structure: Consolidation Pressures and Differentiated Niches
The market is characterized by a moderate concentration at the top, with the largest players holding meaningful but not dominant shares, and a long tail of regional and specialty providers. This structure creates two simultaneous dynamics. First, there is pressure for consolidation among mid-tier and regional firms seeking to achieve scale in staffing, technology deployment, and contract procurement, particularly as compliance and labor costs rise. Second, there is room for differentiation in niches such as high-risk environments, cash and valuables logistics, specialized facility protection, and integrated remote-plus-on-site models. New entrants that can combine technology fluency with disciplined personnel management are finding traction, but they face the same labor and compliance realities as incumbents. The net effect is a market that is neither fully consolidated nor highly fragmented, but one in which strategic positioning—clear service boundaries, credible integration, and reliable execution—is becoming the primary determinant of sustainable share gains.
Future Trends and Commercial Opportunities
Trend One: Hybrid Security Models Will Become the Standard
Over the next three to five years, the distinction between manned and technology-assisted security will increasingly blur into hybrid models that are treated as the baseline offering. Remote monitoring, analytics, and integrated alarm response will be combined with on-site personnel deployed in a more targeted fashion. The commercial opportunity lies in designing service packages that explicitly map technology functions to human responsibilities, so that clients receive a coordinated outcome rather than a stack of separate capabilities. Providers that can demonstrate measurable improvements in response times, coverage efficiency, and reporting clarity will be better positioned to win multi-site and long-term contracts. The risk is that poorly integrated hybrids create confusion about accountability and degrade client trust; therefore, execution discipline and clear service definitions will be critical.
Trend Two: Professionalization of the Security Workforce Will Differentiate Providers
Professionalization—through structured training, clear career pathways, measurable performance standards, and competitive compensation—will move from a nice-to-have to a core competitive requirement. Organizations will increasingly evaluate providers not only on availability and price, but on the quality, consistency, and retention of the personnel assigned to their sites. The opportunity is to build workforce models that reduce turnover, improve service reliability, and create reputational advantage. In commoditized segments, however, wage and staffing pressure will remain a headwind, and providers that lack a clear workforce value proposition will find it harder to defend margins or win complex contracts. The uncertainty lies in the pace of wage escalation across different regions and the extent to which technology can offset labor intensity without compromising service quality.
Trend Three: Regulatory Clarity Will Reshape Market Access and Portfolio Choices
As regulatory frameworks around ownership, procurement, and cross-border private security functions become more defined, market access will be recalibrated. Providers with strong local knowledge, compliant ownership structures, and established relationships will have advantages in certain regions, while others may need to partner, restructure, or refocus their portfolios. The commercial opportunity is to use regulatory intelligence to shape where to compete, how to structure contracts, and which assets to retain or divest. Recent portfolio adjustments by large providers are a reminder that strategic withdrawal from specific segments can free resources for higher-conviction areas. The risk is that regulatory change introduces sudden compliance costs or contract re-bidding, particularly for operators with exposure to government-adjacent or internationally regulated engagements.
Strategic Recommendations for Decision-Makers
For Providers and Operators
Design service models around outcomes, not headcount. Clients increasingly buy protection that is visible, measurable, and integrated, rather than simply the presence of personnel. Providers that can articulate how manned presence, remote support, and reporting work together will command stronger positioning. Invest in workforce stability as a strategic asset: structured training, predictable scheduling, and competitive compensation are not merely cost items; they are the foundation of service quality and client retention. Where commoditization is intense, differentiate through specialization, reliability, or integration rather than price alone, because price competition in a high-turnover environment erodes both margins and reputation.
Managed Security Services System Market
For Investors and Sponsors
Evaluate potential investments with a clear view of labor economics and regulatory exposure. Business models that rely heavily on low-cost staffing without a credible plan for retention and professionalization are exposed to margin volatility and service risk. Preference should be given to operators with demonstrated ability to integrate technology into manned operations in a way that improves coverage and reporting, as well as those with diversified contract bases that reduce dependence on any single public-sector or cyclical customer. Pay close attention to geography and ownership rules, because compliance architecture can either enable scale or constrain it. In markets where concentration is moderate and fragmentation persists, there may be opportunities to build value through disciplined consolidation, shared services, and technology standardization, provided that integration risk is managed carefully.
For Procurement and Risk Leaders
Buy security as a coordinated capability, not as a commodity line item. Define the security mission for each site or portfolio in terms of outcomes—deterrence, response, access control, customer experience, and reporting—then evaluate providers against how they assign responsibilities across personnel and technology. Require evidence of workforce stability, training standards, and escalation protocols, because these factors determine whether service quality holds under stress. Favor contracts that include clear performance metrics, regular reporting, and defined accountability for both on-site and remote components. When regulated environments or cross-border operations are involved, confirm ownership, compliance, and contracting structures early, because late-stage surprises can disrupt delivery and increase cost.
The manned security services market is expanding, but growth alone does not guarantee profitability or competitive advantage. The sector is being reshaped by labor dynamics, regulatory evolution, technology integration, and a more demanding demand base. Organizations that treat these forces as signals to redesign service models, workforce strategies, and portfolio choices will be better positioned to capture value. For those seeking deeper granularity—segment-level sizing, regional dynamics, competitive benchmarking, and tailored scenario analysis—a comprehensive research resource is available to support more precise planning and decision-making.
PW Consulting
For detailed analysis of this topic, please visit the official page: Manned Security Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Medical Shower Chairs Market: Why 5.6% CAGR and Home Care Demand Are Redefining Growth Through 2032
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Medical Shower Chairs Market
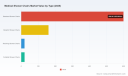
The medical shower chairs market is entering a phase of sustained expansion, driven by demographic shifts and evolving care delivery models. Market revenue climbed from approximately $605.2 million in 2020 to $800.0 million in 2025, reflecting steady year-over-year momentum. Forecasts indicate this trajectory will continue through 2032, with the market projected to surpass $1.1 billion. This growth translates to a compound annual growth rate of 5.6 percent across the 2026–2032 forecast period. The sector’s expansion is not a simple continuation of historical patterns; it reflects structural changes in how mobility support equipment is designed, procured, and reimbursed. Understanding these underlying forces is essential for manufacturers, investors, and procurement leaders seeking to position themselves ahead of market shifts rather than react to them.
Shower Trolley Market
Market growth is being shaped by several concurrent pressures. Aging populations across developed economies are increasing the prevalence of conditions that impair safe bathing, including neurodegenerative diseases and post-surgical mobility limitations. At the same time, healthcare systems are shifting more rehabilitation and long-term care functions into community and home settings. This transition raises demand for equipment that is both clinically appropriate and adaptable to non-institutional environments. A second pressure comes from regulatory scrutiny. Device recalls and adverse event reporting have reinforced expectations around quality system compliance, material durability, and locking mechanism reliability. Manufacturers that treat these as routine compliance exercises risk reputational and operational exposure, while those that embed safety verification into product development cycles are strengthening market trust. A third challenge lies in reimbursement uncertainty. Coverage decisions increasingly hinge on documented medical necessity, functional assessments, and evidence that standard bathing alternatives cannot be used safely. This changes how suppliers must position products and how care providers justify procurement.
Lift Chair Market
Technology Innovation and Clinical Design Shifts
Product development is moving beyond basic seating platforms toward integrated mobility and positioning solutions. Manufacturers are incorporating narrow compact frames, slim wheels, and three hundred and sixty-degree access configurations that reduce caregiver strain and improve maneuverability in tight bathroom layouts. Tilt and recline mechanisms are becoming more refined, with manual and powered options tailored to varying levels of patient independence and caregiver assistance. Color variants and material finishes are also gaining attention, particularly for institutional procurement teams that balance clinical utility with environmental aesthetics and user dignity. These design choices are no longer cosmetic; they are functional differentiators that affect adoption in hospitals, rehabilitation centers, and private homes.
Powered models and modular configurations represent a meaningful breakpoint in the market. Equipment that supports complex positioning criteria for patients with significant physical disabilities is expanding the addressable population beyond users who only need static seating support. This shift aligns with broader trends in person-centered bathing solutions, where the objective is to preserve patient comfort while standardizing safe transfer and hygiene routines. For commercial players, the implication is clear: product portfolios that offer configurable height, tilt, and access features can capture demand across multiple care settings without requiring separate product lines for each segment.
Policy and Reimbursement Dynamics
Reimbursement frameworks are a decisive factor in purchase behavior. Bath and shower chairs are covered under Medicare and Medicaid plans when medically necessary, subject to standardized evaluation criteria that assess whether a patient cannot safely use regular bathtubs or showers. Documentation expectations now commonly include a face-to-face physician examination within a defined period and specialty evaluations from occupational or physical therapists. These requirements shape procurement timelines and influence which products proceed through approval workflows.
Recent policy activity underscores how coverage language can influence category access. In April 2026, a Medicare Advantage organization obtained a favorable ruling in an appeal for coverage of a rolling shower chair that met complex positioning criteria for significant physical disability. This outcome illustrates that coverage is not static; it can expand when clinical justification demonstrates functional need that conventional equipment cannot address. At the same time, supplier cost structures remain uneven. Medicare durable medical equipment supplier costs for rolling shower chairs can exceed four thousand dollars, with reimbursement limited to covered plans under complex positioning requirements. This gap between cost and reimbursement creates pressure on pricing strategies and emphasizes the importance of clear clinical documentation and appropriate coding practices.
Regulatory oversight continues to influence product reliability expectations. Adverse event reports and Class II device recalls involving certain shower chair models have drawn attention to quality system compliance, locking integrity, and load-bearing stability. These developments do not halt market growth, but they sharpen procurement risk assessment. Purchasers increasingly evaluate manufacturers on their ability to demonstrate consistent production controls, traceability, and post-market surveillance. Companies that can provide transparent quality records and rapid issue resolution gain a tangible advantage in institutional tenders and home-care distribution channels.
Demand-Side Behavior and Care Setting Transition
User demand is being reshaped by where care is delivered and who participates in equipment selection. Home care remains the dominant application area, reflecting patient preference, cost containment pressures, and the expansion of outpatient rehabilitation services. Families and home-health providers now prioritize equipment that is easy to install, clean, and store, while still meeting weight capacity and safety requirements. This is especially relevant as more households adapt bathrooms for aging-in-place use rather than relying exclusively on facility-based solutions.
Hospitals and rehabilitation centers continue to be important adopters, but their purchasing logic is evolving. Caregiver safety has become a more explicit procurement criterion, with facilities favoring powered options and designs that reduce manual handling risk during transfers. Long-term care facilities, while smaller in relative volume, provide stable recurring demand and tend to value standardization across units, ease of maintenance, and compatibility with existing hygiene workflows. The commercial implication is that product positioning should not assume a single buying profile. In home care, usability and storage often dominate; in institutional settings, caregiver ergonomics, durability, and documentation compatibility can outweigh other factors.
Supply Chain, Cost Structure, and Procurement Realities
Cost structure pressures are coming from multiple directions. Raw material volatility, component specialization, and the need for repeated safety testing contribute to higher baseline production costs for advanced models. At the same time, reimbursement ceilings and coverage limitations constrain the pricing flexibility of suppliers that depend heavily on public payment pathways. This dynamic is pushing manufacturers to differentiate through configuration rather than price competition alone. Modular designs, accessory ecosystems, and serviceable components can reduce total cost of ownership for facilities that must balance acquisition cost with maintenance and replacement cycles.
Procurement teams are also becoming more disciplined in their evaluation criteria. Safety-tested designs, adjustable height and tilt functions, and clearly documented weight capacities are increasingly treated as baseline expectations rather than premium features. Suppliers that fail to provide clear technical specifications or that rely on vague performance claims face longer approval cycles and greater scrutiny. For distributors, this environment favors inventory 전략의 that align with documented demand patterns in home care and institutional segments, reducing exposure to overstocked SKUs that do not match reimbursement realities or facility specifications.
Competitive Landscape and Leading Strategies
The market remains relatively fragmented, with the top three participants holding roughly twenty-five percent of share and the top five approaching thirty percent. This concentration indicates that no single manufacturer dominates the category, leaving room for differentiated positioning and targeted segment strategies. The market is large enough to support multiple product philosophies, but it is also demanding enough that generic offerings face increasing difficulty in securing both institutional contracts and sustained home-care distribution.
Several leading companies illustrate distinct strategic approaches. ActiveAid emphasizes modular, self-propelled shower and commode chairs with narrow compact frames, slim wheels, three hundred and sixty-degree access, and tilt or recline options. Its recent expansion into broader color variants reflects an effort to support hospital, institutional, and home use with a consistent platform. This approach signals a focus on adaptability and visual integration across environments, which can matter in facilities that value uniformity as well as in home settings where equipment appearance influences user acceptance.
Arjo positions itself around person-centered bathing solutions, offering shower systems, chairs, and trolleys with powered options and caregiver safety features. Its emphasis on diverse mobility levels and powered assistance aligns with the institutional trend toward reducing caregiver strain and standardizing safe bathing routines. By embedding safety and ergonomics into the product narrative, Arjo targets procurement teams that prioritize workforce protection and clinical workflow consistency.
PW Consulting Health Care Research Center
DHG focuses on shower chairs and transfer benches with adjustable features, defined weight capacities, and safety-tested designs for patient comfort in hospital and home settings. This positioning is practical and specification-driven, appealing to buyers who need clear performance parameters and repeatable configurations. DHG’s approach highlights the commercial value of transparent technical documentation and product consistency across settings.
Etac provides shower commodes such as Alto, Swift Mobil, and Swift Mobil Tilt-2, with powered or manual options, three hundred and sixty-degree access, ergonomic design, and adjustable height or tilt. Its portfolio supports both user and caregiver needs, which is particularly relevant where patient mobility varies widely within the same facility or household. Etac’s broader international heritage, combined with U.S. market presence, also illustrates how established design reputations can support credibility in a category where safety and usability are closely scrutinized.
Invacare offers the I-Fit shower chair and Ocean series with tilt or recline, powered models, and accessories for bariatric and standard users. Its breadth across weight classes and feature levels reflects a strategy of covering multiple patient profiles with interconnected product lines. This can simplify catalog management and cross-selling, but it also requires rigorous quality oversight given that shower chair models in this category have appeared in adverse event reporting and recall activity. The lesson for competitors is consistent: product variety must be matched by disciplined production and post-market controls.
The overall competitive pattern suggests a market that rewards specialization without sacrificing platform flexibility. Leaders are differentiating through powered access, modular framing, caregiver-centric safety features, and clearer documentation of use cases and capacities. At the same time, market evolution is likely to see continued consolidation pressure among smaller suppliers who cannot sustain compliance costs or distribution reach, while new entrants may focus on underserved niches such as compact home-use configurations, bariatric-specific designs, or equipment that integrates more smoothly with existing bathroom layouts.
Future Trends and Commercial Implications
Over the next three to five years, one major trend will be the continued expansion of powered and complex positioning solutions. As reimbursement pathways for advanced models become clearer through case-by-case appeals and updated clinical criteria, demand for tilt, recline, and powered mobility options should increase, particularly in rehabilitation and complex-disability settings. This opens commercial opportunities for manufacturers that can prove functional benefit and support documentation workflows, but it also raises the bar for engineering reliability and service support.
A second trend is the deepening alignment between product design and home-care adoption. As more bathing support equipment is procured for private residences, buyers will favor designs that combine safety with straightforward installation, cleaning, and storage. Manufacturers that offer compact frames, secure locking mechanisms, and materials suited to frequent sanitation will be better positioned in this channel. There is also room for bundled accessories and configuration guidance that help families and home-health providers match equipment to specific bathroom constraints.
A third trend is the growing influence of risk and compliance visibility in purchasing decisions. Given ongoing recalls and adverse event reporting, procurement teams are likely to place greater weight on quality system transparency, post-market monitoring, and documented testing. Suppliers that can communicate their compliance processes clearly and respond quickly to issues will gain trust. This creates an opportunity for companies to build reputation capital around reliability, not just product features. The associated risk is that regulatory attention may continue to affect specific models and production batches, requiring manufacturers to maintain agile quality controls and proactive communication.
Actionable Guidance for Decision Makers
Manufacturers should prioritize platform flexibility over narrow feature competition. Equipping product lines with modular tilt or recline options, clear weight classifications, and caregiver-friendly access designs can expand addressable demand across home care, hospitals, and long-term care facilities without fragmenting production. Equally important is investing in documentation that supports medical necessity pathways and procurement evaluation, since reimbursement clarity and specification transparency increasingly determine purchase speed.
Investors should evaluate exposure to advanced positioning and powered models, as well as the strength of each company’s quality and compliance infrastructure. Growth in the category is likely, but returns will be shaped by which participants can manage cost structure pressures, maintain reimbursement-relevant documentation, and respond effectively to safety scrutiny. Portfolio concentration in home-care-friendly configurations and bariatric-capable designs may provide resilience across economic and reimbursement cycles.
Procurement leaders should standardize evaluation criteria around safety-tested design, adjustable height and tilt, defined weight capacity, locking reliability, and documentation compatibility. Rather than selecting products on appearance or price alone, purchasing teams can reduce downstream risk by aligning acquisitions with caregiver workflow needs and patient positioning requirements. For facilities managing mixed user profiles, configurable platforms can reduce inventory complexity while preserving appropriate clinical support.
The commercial landscape in this market is evolving quickly enough that strategic decisions benefit from current segment definitions, regional demand patterns, and reimbursement detail. A deeper view of these dynamics can help organizations translate broad trends into product, pricing, and procurement choices that are better aligned with near-term reality. Readers seeking a more granular breakdown of market segments, share shifts, and actionable entry points can refer to the complete PW Consulting market research report for detailed segmentation data and tailored recommendations.
For detailed analysis of this topic, please visit the official page: Medical Shower Chairs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Beneath the Surface: Strategic Trends and Commercial Opportunities in the Marine Trenchers Market
The marine trenchers market has entered a phase of steady structural expansion, underpinned by growing offshore infrastructure investment and evolving technical requirements for subsea installation. Valued at approximately 120.0 million USD in 2020, the market reached an estimated 148.5 million USD by 2025, reflecting a compound annual growth rate of 4.0 percent over the 2020–2025 period. Forward projections extend through 2032, with revenue anticipated to approach 195.5 million USD by the end of the forecast horizon. While the growth trajectory appears measured in percentage terms, the underlying shift in project complexity, operational depth, and equipment specialization tells a more dynamic story. Marine trenching has moved from a supporting activity in pipeline and cable deployment to a critical capability that directly influences project economics, environmental compliance, and operational risk.
Several inflection points define the current market environment. First, the push toward deeper water projects and more complex seabed conditions is placing new demands on trenching systems, particularly around tool interchangeability, remote operation, and sediment adaptability. Second, rising project costs linked to maintenance, specialized labor, and equipment wear are forcing operators to prioritize reliability and lifecycle performance rather than upfront price comparisons. Third, the growing emphasis on offshore wind, interconnectors, and gas infrastructure is expanding the number of burial and trenching campaigns, but also compressing scheduling windows and increasing the premium on proven, repeatable execution. These dynamics are not merely operational concerns; they are reshaping procurement strategies, fleet planning, and competitive positioning across the supply chain.
Key Drivers Shaping the Market Trajectory
Technological Innovation and the Shift Toward High-Performance, Multi-Mode Systems
One of the most visible drivers in the marine trenchers market is the continued advancement of equipment capability. The industry is moving beyond single-purpose designs toward systems that can switch between mechanical cutting, jetting, and hybrid modes depending on sediment type and burial depth. This flexibility is increasingly valued because seabed conditions are rarely uniform, and project specifications often require precise depth control, minimal surface disturbance, and adaptable tool configurations. Higher horsepower platforms, improved hydraulic and electro-hydraulic architectures, and more robust cutting chains and bits are enabling operators to maintain productivity in harder sediments where wear rates and ground speed have historically limited performance.
Recent equipment milestones illustrate this direction. In October 2025, Osbit Ltd secured a contract with NKT to design and build the T3600 subsea trencher, described as one of the most powerful systems in the segment with 3,600 horsepower and dual jetting and cutting tools. The concept reflects a broader preference for machines that can handle heavier workloads while reducing the need for multiple vessel-based interventions. By February 2026, the T3600 had arrived at the Port of Blyth for final fit-out and commissioning ahead of operational use in 2027. This kind of development signals an industry leaning toward higher-capacity platforms that can address longer burial campaigns, more demanding ground conditions, and tighter project schedules.
For decision-makers, the implication is clear: equipment selection is becoming less about whether a trencher can complete a burial task and more about how effectively it can do so across variable conditions, with lower downtime and fewer operational compromises. Manufacturers that can demonstrate measurable improvements in tool life, ground speed stability, and mode switching are better positioned to capture perceived value, even when capital or rental costs are higher.
Policy, Regulation, and the Spreading Footprint of Offshore Infrastructure
Regulatory and policy environments are exerting a quiet but persistent influence on trenching demand. Environmental standards, seabed protection requirements, and cable and pipeline burial specifications are increasingly factored into project design, which in turn raises the baseline expectation for trenching quality and consistency. In many regions, burial is no longer treated as a discretionary step; it is a core requirement for protection against fishing activity, anchor damage, and environmental disturbance.
Broader energy and infrastructure trends reinforce this direction. European offshore wind capacity reached approximately 25 GW by 2020, and the continued expansion of wind farms and interconnector networks has sustained demand for cable burial equipment and related trenching standards. At the same time, Europe imported 85 billion cubic meters of LNG in 2020, helping accelerate demand for subsea pipeline burial and associated marine trenching in the region. These figures are not just energy statistics; they represent the kind of large-scale infrastructure activity that creates recurring requirements for burial, rehabilitation, and intervention services.
The policy-driven opportunity is twofold. Projects are increasingly spread across multiple geographies and seabed environments, which broadens the addressable market for trenching equipment and services. At the same time, regulatory expectations can raise the bar for execution, favoring operators with documented quality control, traceability, and compliance capabilities. Procurement teams are likely to weigh not only schedule and cost, but also the ability to meet region-specific burial standards and environmental safeguards.
Demand-Side Changes: More Burial Work, More Complexity, More Coordination
Demand for marine trenchers is being shaped by a shift in how offshore projects are planned and executed. Cable and pipeline installations are no longer isolated activities; they are integrated into wider grid, gas, and industrial networks that require coordinated scheduling across multiple contractors and vessels. As a result, trenching work is often planned around limited weather windows, restricted seabed access, and tight connection milestones. This places a premium on equipment availability, predictable performance, and rapid mobilization.
Pipeline burial remains the largest application area in terms of revenue contribution, reflecting the continued importance of protected subsea transport infrastructure. Cable burial is also significant, driven by interconnectors, wind farm export and array cables, and telecommunications links. Umbilical burial represents a smaller but technically demanding segment, often involving more delicate handling requirements and specialized burial approaches. The practical takeaway is that demand is diversified across infrastructure types, but the common thread is a need for burial solutions that can be deployed reliably across different project phases and seabed conditions.
For buyers and operators, this means that trenching capability is being evaluated within a broader project ecosystem. Equipment that can be integrated easily with different vessel configurations, ROV support, and survey and monitoring workflows is more attractive than a standalone machine optimized for a narrow set of conditions. The market is rewarding flexibility and service integration as much as raw trenching power.
Cost Structure and Operational Pressures: Wear, Labor, and Maintenance
Cost dynamics remain a significant driver of purchasing and operating behavior. Subsea trenching operations face elevated costs when sediment conditions accelerate chain and bit wear, especially in harder ground where achievable ground speeds and component life must be carefully managed. Performance monitoring against established geotechnical reference frameworks has become a practical necessity rather than an academic exercise, because underestimated wear or overly optimistic speed assumptions can materially affect project budgets and schedules.
Labor and maintenance costs add another layer of pressure. Specialized subsea trenching maintenance and operator training contribute meaningfully to overall project expenses, particularly for offshore infrastructure campaigns that require sustained operational readiness. High skill requirements, limited pools of experienced personnel, and the cost of keeping complex systems in field-ready condition all feed into total cost of ownership. This is an important shift from a purely equipment-purchase mindset to a broader operating-cost perspective.
Worldwide Underwater Dredging Robot Market
Recent project activity highlights how these cost and performance considerations play out in practice. In April 2025, Van Oord added a new Jet-It subsea trencher to its cable burial fleet following successful North Sea testing, reinforcing the value of proven shallow-water cable burial capability. In January 2025, DeepOcean completed a subsea trenching project in the US Gulf of Mexico using a 2,800hp trencher for cable and pipeline burial, demonstrating the continued relevance of powerful mechanical and jetting systems in active offshore regions. These deployments show that performance validation in real seabed conditions is a decisive factor in fleet expansion and project award decisions.
PW Consulting
Competitive Landscape and Leading Strategies
The marine trenchers market is characterized by a concentrated but diverse set of participants. Market concentration is notable, with the top three companies accounting for roughly 62.0 percent of revenue and the top five firms holding about 78.0 percent. This level of concentration suggests that scale, technological reputation, and established project relationships matter significantly, while still leaving room for specialized players and regional specialists to compete on differentiated capabilities.
Several companies illustrate the range of strategic positions in the market. Soil Machine Dynamics Ltd, based in Wallsend, Tyne & Wear, United Kingdom, manufactures subsea trenchers, burial machines, and related intervention equipment for pipeline and cable laying, including the Q-Trencher and Shallow Water Trencher models. Royal IHC, headquartered in Kinderdijk, Netherlands, designs and manufactures the Hi-Traq® multi-tool subsea trenchers, jetters, and tracked trenching vehicles for shallow water cable burial and offshore wind projects. Seatools B.V., based in the Netherlands, specializes in custom subsea trenching vehicles, mechanical and jet trenchers, cable ploughs, and upgrades for pipeline and cable installations. Osbit Ltd, also in the United Kingdom, designs, builds, and upgrades subsea trenching systems including mechanical, jetting, and cutter trenchers for cable and pipeline burial. Mastenbroek Limited, another UK-based manufacturer, provides subsea trenchers with conventional or undercut/rotary heads, available in hydrostatic or electro-hydraulic configurations for various sediment types.
The competitive field also includes operators and integrated service providers that use or deploy trenching equipment as part of broader campaign execution. Allseas Group, based in the Netherlands, operates Digging Donald, a fully remote-controlled pipeline burial trencher capable of depths up to 450 meters with interchangeable tools. DeepOcean Group, headquartered in the United Kingdom, operates a fleet and provides marine trenching equipment including mechanical trenchers, jetting ROVs, and ploughs for pipeline, cable, and umbilical burial. Van Oord, also in the Netherlands, operates and manufactures its own fleet of trenchers including Deep Dig-It, Dig-It, and Jet-It for subsea cable burial up to more than 5 meters below the seabed.
Differentiation Through Capability, Flexibility, and Execution track Record
What distinguishes the stronger positions is not simply equipment ownership, but the ability to match trenching technology to project needs and to prove performance in the field. Some manufacturers compete on power and tool versatility, emphasizing high horsepower and dual-mode systems that can adapt to harder or mixed sediments. Others compete on specialization, focusing on shallow water cable burial, tracked vehicles, or custom trenching vehicles that can be tailored to specific seabed and water-depth constraints. A third group differentiates through remote operation, depth capability, and tool interchangeability, which matters when projects require precise burial at greater depths or when surface vessel exposure must be minimized.
Recent developments show how these strategies are being reinforced. The T3600 contract award to Osbit and its subsequent arrival for fit-out point to a push toward higher-power, multi-tool systems that can serve demanding pipeline and cable projects. Van Oord's addition of a new Jet-It trencher after North Sea testing reflects a practical emphasis on validated cable burial performance in a region with active wind and interconnector work. DeepOcean's Gulf of Mexico project completion demonstrates the value of proven fleet deployment in geographically diverse markets.
Market Evolution: Consolidation, Specialization, and Selective New Entry
The market is likely to continue evolving around three themes. First, consolidation may remain attractive for firms seeking to broaden geographic reach, capture more of the project lifecycle, or combine equipment manufacturing with service delivery. Second, specialization will persist because seabed conditions, water depths, and project types are too varied for a single equipment architecture to dominate all segments. Shallow water cable burial, deep pipeline burial, umbilical handling, and mixed-sediment trenching each reward different design priorities. Third, new entry and expansion will depend on credible technical differentiation and demonstrated execution, rather than brand presence alone. In a market where top suppliers already hold a substantial share, credibility is built through project record, performance data, and the ability to integrate with operator and client workflows.
For strategic planners, the competitive takeaway is that procurement is increasingly comparative and evidence-based. Vendors that can articulate measurable differences in wear performance, operating efficiency, and deployment flexibility are better placed to defend pricing and win repeat work. For investors and industry participants, the more interesting question is not whether the market will grow, but which capabilities will be rewarded as project conditions become more varied and cost scrutiny intensifies.
Future Trends to Watch Over the Next 3 to 5 Years
Trend 1: Higher-Capacity, Multi-Mode Trenching as a Baseline Expectation
Over the next few years, the threshold for competitive trenching capability is likely to rise. Projects in harder sediments, deeper water, and more constrained schedules will push operators toward higher horsepower platforms with interchangeable tools and multiple burial modes. The recent emphasis on powerful dual-function systems is not an isolated product trend; it reflects a broader expectation that trenching equipment should reduce the need for rework, handle variable ground conditions, and keep campaigns on schedule.
The commercial opportunity here lies in equipment and service packages that lower total operating risk rather than simply increase peak power. Manufacturers and fleet providers that pair high-capacity machines with proven tool management, maintenance planning, and operational support may find stronger demand than those competing on hardware specifications alone. The risk is that power upgrades can raise capital and maintenance costs, so any advantage must be translated into measurable gains in productivity, component life, or schedule reliability.
Trend 2: Greater Integration of Remote Operation, Monitoring, and Fleet Standardization
Remote-controlled and remotely supervised trenching is likely to become more prominent as projects seek to improve precision, reduce vessel exposure, and standardize execution across multiple sites. The growth of fully remote pipeline burial systems and ROV-supported jetting and mechanical trenchers indicates a market moving toward operational models that depend less on manual intervention and more on controlled, repeatable processes. At the same time, operators managing multiple vessels and campaigns will increasingly value fleet standardization, common maintenance regimes, and shared training pathways.
Marine Deck Machinery Market
This trend creates opportunities for companies that can offer not just equipment, but consistent operating interfaces, training support, and lifecycle management. For buyers, standardized fleets and remote operation can simplify crew deployment and reduce variability between projects. The uncertainty is operational maturity: remote and semi-remote systems require dependable communications, maintenance readiness, and skilled oversight, so the benefits will depend on how well they are integrated into real-world campaign planning.
Trend 3: Regional Demand Diversification with Uneven Pace
Demand for marine trenching is expected to remain geographically diverse, supported by offshore wind, interconnectors, pipeline and cable networks, and energy infrastructure expansion in multiple regions. However, the pace of growth is unlikely to be uniform. Some markets will see sustained activity driven by large-scale wind and grid investments, while others may experience more intermittent demand tied to specific pipeline or LNG-related projects. This uneven pattern means that fleet planning and regional positioning will matter more than broad but shallow market exposure.
The associated opportunity is to align equipment portfolios and service coverage with the regions and project types most likely to generate recurring work. Companies that understand local seabed conditions, regulatory expectations, and project scheduling realities will be better positioned to capture demand without overextending into less predictable segments. The main risk is overgeneralizing from one region's pipeline or wind activity to the entire market; seabed conditions, permitting environments, and vessel logistics vary enough to make regional nuance a strategic necessity.
Strategic Recommendations for Decision-Makers
For manufacturers and equipment developers, the priority should be to translate technical differentiation into commercial clarity. Higher power, multi-mode tools, and remote operation features are attractive, but their value increases when they are linked to measurable outcomes such as reduced rework, longer component life in challenging sediments, and faster mobilization. Investment in demonstration projects, peer-reviewed performance data, and lifecycle support can be as important as the hardware itself. Companies should also consider how their offerings fit into broader project ecosystems, including compatibility with different vessel types, ROV support, and survey workflows.
For investors and strategic partners, the most defensible opportunities are likely to be found where market concentration, technical lead times, and execution track record intersect. A concentrated market can create durable positions for firms with proven capability, but it also means that competitive advantage must be continually renewed through product evolution and reliable project delivery. Capital allocation decisions should account for the reality that trenching demand is tied to large infrastructure cycles, which can be strong but unevenly timed. Preference for operators and manufacturers with diversified project exposure, disciplined cost structures, and credible maintenance and training capabilities may offer a more balanced risk profile than pure capacity expansion.
For procurement teams and project developers, equipment selection should be evaluated against total project risk rather than headline performance alone. Burial depth requirements, sediment variability, maintenance readiness, training burden, and regional support availability all influence long-term outcomes. Where possible, validation through recent deployments in comparable conditions can provide more useful guidance than specification comparisons in isolation. Buyers may also benefit from considering fleet compatibility and service integration, especially when multiple projects or regions are involved, because standardization can reduce training costs and improve scheduling predictability.
Across all perspectives, the most valuable intelligence is the kind that connects equipment capability to real operational conditions and project economics. Market size and growth rates provide context, but the decisions that matter most are usually about which trenching approach fits a given seabed profile, which fleet configuration best supports regional demand, and which performance trade-offs are acceptable when wear, labor, and maintenance costs are factored in. Detailed segmentation data, company-level positioning, and region-specific demand analysis can make those choices sharper and less reliant on assumption.
Closing Perspective
The marine trenchers market is expanding at a steady pace, but its strategic significance is growing faster than the headline numbers suggest. Burial and trenching are increasingly integral to the safe, compliant, and cost-effective deployment of offshore pipelines, cables, and umbilicals. That shift rewards systems that combine power, flexibility, remote operability, and proven field performance, while also rewarding operators and manufacturers that can manage the practical realities of wear, specialized labor, and project scheduling. The next several years will likely favor participants who treat trenching capability as part of an integrated infrastructure solution rather than as a standalone tool purchase. For executives, investors, and procurement leaders, the most useful next step is to align equipment and service choices with the specific seabed conditions, regional demand patterns, and cost structures that will shape each project's outcome.
For detailed analysis of this topic, please visit the official page: Marine Trenchers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Why Are Enclosed Trailers a Smart Choice for Protecting and Transporting Your Belongings?
By traileroutletva, 2026-09-21
Transporting tools, supplies, furniture, or personal gear can be much easier with the right trailer. An enclosed trailer provides a covered space where items can stay protected during travel and storage. For people comparing enclosed trailers for sale , this design offers a practical way to move belongings without exposing them to rain, dust, road debris, or direct sunlight. Whether the trailer is used for work or personal projects, its enclosed structure can make hauling more convenient.
How Does an Enclosed Trailer Protect Your Belongings?
The biggest advantage of an enclosed trailer is its protective design. Unlike an open trailer, it has solid walls, a roof, and doors that surround the cargo. As a result, belongings have less exposure to changing weather and outside conditions.
Rain can damage tools, furniture, electronics, and other materials. Dust and road dirt can also make equipment messy during transportation. An enclosed trailer creates a barrier between these items and the outside environment. This simple feature can save time because there may be less cleaning or drying to do after every trip.
Security is another benefit. Since the cargo is kept behind closed doors, it is not as visible to people passing by. While proper locks and security practices are still important, keeping valuable equipment out of sight can provide an added layer of protection.
Why Are Enclosed Trailers Useful for Contractors?
Contractors often need to transport several tools and supplies from one job site to another. Carrying everything in a vehicle may not provide enough room. An enclosed trailer offers additional storage space while keeping equipment organized.
Power tools, ladders, hand tools, safety equipment, and materials can all be arranged inside. Shelving, cabinets, racks, and tie-down systems can make the interior even more useful. Therefore, workers can spend less time searching for equipment and more time getting the job done.
An enclosed trailer can also serve as a mobile storage area. Contractors who move between multiple job sites may appreciate having their commonly used equipment in one dedicated space.
Can Small Businesses Benefit From an Enclosed Trailer?
Absolutely. Small businesses often need flexible ways to transport products, supplies, displays, or equipment. A trailer can provide extra room without requiring a larger commercial vehicle. For example, a landscaping business can carry tools and equipment, while a mobile service provider can use the trailer to transport machines and supplies. Event businesses can haul decorations, tables, lighting equipment, and other materials.
For growing businesses, this extra space can also make daily operations more organized. Instead of packing and unpacking a vehicle every day, workers can keep frequently used items inside the trailer and restock when necessary.
What Makes Enclosed Trailers Practical for Personal Use?
Enclosed trailers are not just for businesses. Homeowners can find plenty of uses for them, too. Moving furniture, transporting bicycles, carrying camping equipment, or handling large home improvement projects can become easier with additional enclosed space.
Families who enjoy outdoor activities may use a trailer to carry bikes, sports equipment, camping gear, or recreational supplies. Because everything stays inside, there is less concern about items being exposed during a long drive.
They can also be useful during a move. Furniture and household belongings can be loaded into the trailer and kept covered throughout the trip. That can be especially helpful when traveling through unpredictable weather.
What Should You Consider Before Buying One?
Choosing from enclosed trailers for sale requires more than simply picking the largest option. First, consider what you plan to transport regularly. Think about the size, weight, and shape of your typical cargo.
Next, look at the trailer's interior height and width. Taller equipment may need additional clearance, while bulky items may require wider doors. You should also consider the trailer's weight capacity and make sure your towing vehicle can handle the loaded trailer safely.
Features matter, too. Rear doors, side doors, interior lighting, flooring, shelving, tie-down points, and ventilation can all affect how useful the trailer becomes.
Buyers looking for an enclosed trailer for sale in Virginia should also think about how frequently the trailer will be used. A trailer used every day may require a more durable setup than one used only for occasional home projects.
How Can an Enclosed Trailer Improve Daily Efficiency?
An enclosed trailer can do more than transport cargo from one place to another. It can help create a more organized workflow. When tools and supplies have designated spaces, loading and unloading becomes easier.
There is also less need to make multiple trips. Instead, users can carry more equipment in one journey, provided the load remains within the trailer's safe capacity. Over time, these small improvements can make regular hauling tasks much smoother.
For businesses, better organization can also create a more professional working routine. Employees know where equipment belongs, and important supplies are easier to locate when needed.
Is an Enclosed Trailer a Long-Term Investment?
For frequent hauling needs, an enclosed trailer can be a practical long-term investment. It combines transportation, storage, and protection in one solution. With proper maintenance, tires, brakes, lights, doors, and other components can continue supporting regular use for years.
The key is choosing a trailer that matches the intended workload. A trailer that is too small may become inconvenient, while one that is unnecessarily large can add towing costs and reduce maneuverability.
Whether used for business operations, home projects, recreation, or moving, an enclosed trailer offers a flexible way to transport belongings while keeping them covered and organized. For many users, that combination of protection, storage, and convenience makes an enclosed trailer worth considering.
Ballast Water Treatment Equipment Market: Why 8.7% CAGR Changes Everything
By pmarketresearch, 2026-09-21
The Ballast Water Treatment Equipment Market: Navigating the Next Wave of Maritime Compliance and Capital Opportunities
The global fleet is undergoing a quiet but profound transformation. As environmental regulations tighten and port state inspections become more rigorous, ballast water treatment has shifted from a compliance checkbox to a strategic operational priority. The market has expanded at a steady pace, with revenues crossing the seven-billion-dollar threshold in 2025 and projected to surpass ten billion before 2030, maintaining a compound annual growth rate of 8.72 percent through 2032. This trajectory reflects more than incremental fleet upgrades; it signals a structural realignment in how shipowners, regulators, and technology providers approach ballast water management as a long-term operational and sustainability imperative.
Growth is broad-based, spanning mature and emerging maritime regions, with Asia Pacific representing the largest share of activity, followed by Europe and North America. While the regional distribution reflects differing fleet compositions and regulatory timelines, the underlying momentum is universal: older vessels are being retrofitted, newbuilds are specifying treatment systems at the design stage, and operators are seeking equipment that balances performance with minimal downtime. Against this backdrop, the market is no longer defined solely by regulatory compliance deadlines. It is increasingly shaped by technology maturity, cost-of-ownership dynamics, and the growing emphasis on electronic record-keeping and verifiable treatment performance under intensifying inspection regimes.
Market Landscape and Core Challenges
The current phase of the ballast water treatment equipment market is characterized by a maturing technology base, heightened enforcement activity, and a competitive environment that favors players capable of demonstrating reliable performance across diverse water conditions and vessel types. Revenue growth has been consistent, supported by a pipeline of retrofit projects and newbuild specifications. Yet beneath the headline figures lie structural tensions that will determine which companies and investors capture durable value.
1. Treatment Performance Under Real-World Variability
Ballast water systems must handle wide fluctuations in salinity, temperature, turbidity, and biological load. This variability continues to challenge system reliability, particularly for technologies sensitive to water quality or requiring precise chemical dosing. Operators are increasingly scrutinizing performance data, service histories, and the ease of maintenance when selecting equipment. The implication is clear: systems that can demonstrate consistent efficacy with simpler maintenance profiles, and that integrate cleanly into existing vessel operations, are gaining preference over solutions that demand frequent calibration or extensive crew intervention.
2. Regulatory Tightening and Inspection Pressure
The regulatory environment is moving from baseline compliance toward verifiable, auditable performance. Recent amendments to the Ballast Water Management Convention have updated record-keeping requirements, including revised Ballast Water Record Book forms and the introduction of electronic records, reinforcing the expectation that operators maintain detailed, accessible documentation. Concurrently, port state control concentrated inspection campaigns have targeted ballast water management during specific windows, employing structured questionnaires and on-site verification to assess system compliance. These developments elevate the importance of systems that not only meet technical standards but also facilitate transparent reporting and straightforward audits.
3. Capital Allocation and Retrofit Economics
Shipowners face competing capital priorities, particularly in an environment where dry-dock schedules, compliance upgrades, and operational efficiency investments all compete for limited budgets. Retrofitting ballast water treatment equipment requires careful planning around vessel downtime, installation complexity, and integration with existing piping and control systems. For fleet operators, the decision often hinges on total cost of ownership rather than upfront price alone, including energy consumption, consumables, service availability, and the potential for future regulatory changes. This dynamic is reshaping procurement behavior toward solutions that offer predictable operating costs and adaptable configurations.
Key Drivers Redefining Market Dynamics
Several interconnected forces are accelerating growth and reshaping competitive priorities in the ballast water treatment equipment market. Understanding these drivers is essential for identifying where demand is heading and which capabilities will differentiate successful participants.
Technology Innovation and Treatment Modality Evolution
The technology landscape reflects a shift toward hybrid and multi-barrier approaches that combine filtration with disinfection methods such as ultraviolet treatment, electrolysis, and chlorine-based disinfection. Filtration-plus-UV configurations are widely recognized for their chemical-free operation and suitability across many vessel types, while electrolysis-based systems offer compact footprints and strong disinfection performance. Chlorination-focused solutions provide effective treatment in certain operating conditions but require careful handling and monitoring. The practical trend is toward systems that can adapt to varying ballast water quality, minimize consumables dependency, and integrate smoothly with vessel automation and data systems. This is not merely a technical preference; it reflects operational priorities around crew workload, maintenance intervals, and regulatory verifiability.
Policy and Regulatory Momentum
Policy remains the foundational demand driver, but its influence is deepening beyond initial compliance. The ongoing review of the ballast water management framework, informed by accumulated data and operational experience, points to potential amendments that could further refine performance requirements and measurement approaches. For manufacturers and shipowners alike, this means designing for future-proofing. Systems that are modular, upgradable, and capable of producing auditable electronic records will be better positioned as the regulatory framework evolves. The emphasis on documentation and verification also raises the strategic importance of service and support, since compliance is increasingly judged by both equipment performance and the quality of operational records.
Demand-Side Shifts in Fleet Strategy
Shipowners and operators are recalibrating fleet strategy in response to energy efficiency goals, operational resilience, and reputational considerations. Ballast water treatment is now part of a broader conversation about vessel sustainability and operational risk management. Newbuild orders increasingly include treatment specifications as standard, while retrofit activity is being prioritized for vessels with longer remaining service lives. This demand-side shift favors solutions that can be installed with minimal disruption, integrated with existing bridge and automation systems, and supported by local service networks. In addition, operators are increasingly factoring in the ease of proving compliance during inspections, which makes system transparency and documentation support a material purchasing consideration.
Supply Chain and Cost Structure Pressures
Cost structures in the equipment and services space are being re-evaluated as operators seek to manage total expenditure over the lifecycle of the vessel. While initial pricing remains relevant, buyers are paying greater attention to energy use, filter replacement cycles, chemical handling where applicable, and the availability of service and spare parts across key operating regions. This has encouraged a broader view of value, with some operators favoring solutions that reduce recurring consumable costs or that offer service agreements aligned with planned maintenance schedules. At the same time, supply chain resilience matters, particularly for components that must be available across multiple regions and vessel types. Providers that can combine reliable hardware with predictable service delivery are increasingly differentiated.
Competitive Positioning and Strategic Differentiation
The competitive landscape is moderately concentrated, with a handful of leading firms accounting for a significant share of activity. This concentration reflects the credibility requirements of the market: shipowners prefer suppliers with established certification status, proven installation experience, and the ability to support vessels across regions. At the same time, the diversity of treatment technologies and vessel requirements leaves room for specialized offerings and regional strengths.
Technology Archetypes and Differentiators
Leading participants are building distinct identities around treatment architecture, service capability, and integration depth. Alfa Laval, for example, has focused on filtration-plus-UV systems with an emphasis on compact design and compatibility with a range of vessel types, positioning its PureBallast product line around operational simplicity and performance consistency. Techcross has emphasized electrochemical approaches through direct and indirect electrolysis systems, catering to operators seeking robust disinfection performance and a footprint suited to certain vessel configurations. Hyde Marine’s Guardian series combines filtration and UV treatment with a focus on reliability and installation flexibility. Optimarin offers filtration-plus-UV systems with a strong service orientation, while De Nora Marine and Evoqua Water Technologies are associated with filtration-plus-electrolysis architectures that appeal to operators prioritizing disinfection performance and compact layouts. Wärtsilä presents both UV and electrochemical options, leveraging broad marine system integration capabilities. Norwegian Greentech, Trojan Marinex, and Ecochlor round out a field that includes filtration-plus-UV and filtration-plus-chlorine disinfection approaches, each with distinct operating trade-offs.
The strategic implication is that no single technology archetype dominates across all segments. Instead, differentiation is emerging around the fit between treatment method and vessel profile, the quality of documentation and inspection readiness, and the reliability of regional service support. Companies that can articulate clear performance cases, provide robust training and maintenance pathways, and align their offerings with electronic record-keeping expectations are likely to strengthen their position as scrutiny intensifies.
Concentration, Consolidation, and Market Evolution
The market’s moderate concentration suggests room for both consolidation and targeted fragmentation. Larger players with integrated marine system portfolios can leverage cross-selling, service networks, and engineering partnerships to deepen their footprint. At the same time, specialized manufacturers and regional service providers can compete by offering niche performance advantages, faster installation, or customized support for specific vessel types. Recent certification updates from classification bodies have reaffirmed approvals for a broad set of manufacturers, underscoring that the market remains open to multiple qualified participants. This environment favors companies that can demonstrate not only technical compliance but also the operational credibility to withstand inspection campaigns and evolving record-keeping expectations.
A further evolution likely to shape the competitive landscape is the increasing importance of digital readiness. Systems that produce clean, auditable data trails and interface with vessel reporting processes are better positioned for the inspection environment and the broader movement toward electronic records. This is not only a compliance consideration; it is becoming a differentiator in how operators assess risk, manage audits, and maintain documentation across fleets.
Strategic Outlook: Trends Shaping the Next Three to Five Years
Looking ahead, several trends are likely to define the direction of the ballast water treatment equipment market and its commercial opportunities.
1. Compliance Becomes Continuous, Not Episodic
As inspection activity intensifies and electronic record-keeping becomes standard, the market will increasingly value systems that support ongoing verification rather than one-time certification. This trend favors solutions with clear documentation outputs, straightforward maintenance, and service models that help operators sustain compliance over time. For equipment providers, the opportunity lies in embedding compliance support into the product experience and service package, reducing the administrative burden on shipowners while strengthening reliability during audits.
Commercial implication: Providers that combine robust hardware with documentation-ready workflows, crew training, and localized service can create stickier relationships and reduce attrition in competitive retrofit and newbuild decisions.
2. Technology Convergence Around Practical Performance
While multiple treatment modalities will persist, the market is likely to see greater emphasis on practical performance across variable water conditions, ease of maintenance, and compatibility with vessel systems. Hybrid approaches that pair pre-treatment filtration with a disinfection method selected for the operating profile will remain central. Over the next few years, differentiation will increasingly hinge on real-world reliability, energy efficiency, and the ability to adapt configurations to specific vessel types and routes. This could encourage more modular designs and more flexible service agreements.
Commercial implication: Manufacturers that invest in field performance data, simplify maintenance, and align configurations to vessel operating patterns can strengthen their value proposition beyond compliance certification alone.
3. Regulatory Refinement Will Reshape Requirements and Planning Horizons
The ongoing review of the ballast water management framework, informed by operational data, suggests that requirements could evolve. Potential amendments may influence measurement approaches, reporting expectations, or performance verification methods. For shipowners and builders, this means adopting a forward-looking procurement stance, favoring systems that can be updated or reconfigured without major rework. For suppliers, it means designing products and service offerings with regulatory adaptability in mind.
Commercial implication: Early alignment with likely regulatory directions can reduce future retrofit risk and position companies to capture demand from operators seeking durable, adaptable solutions rather than short-term compliance fixes.
Worldwide Black Water Treatment System for Boats Market
Risks and Uncertainties to Monitor
No strategic outlook is complete without acknowledging uncertainty. The pace and content of future regulatory amendments remain dependent on international consensus and technical review processes. Inspection campaigns can vary in intensity and focus across regions, affecting short-term demand patterns. Economic conditions, vessel utilization, and capital availability will influence the timing of retrofit investments, particularly for older tonnage. In addition, technological trade-offs among treatment methods mean that performance claims must be carefully matched to specific operating conditions, and that supplier claims should be validated against real-world service data where possible.
PW Consulting
These uncertainties do not diminish the long-term trajectory; they reinforce the value of informed, scenario-aware decision-making. The operators and investors who succeed will be those who treat ballast water management not as a single compliance event but as a continuing operational capability.
Actionable Recommendations for Decision-Makers
For manufacturers, investors, and procurement teams, the current market environment calls for a balanced focus on compliance credibility, operational practicality, and lifecycle economics.
Water Treatment Equipment Market
For Equipment Manufacturers and Technology Providers
Position offerings around verifiable performance and inspection readiness, not certification alone. Invest in field performance documentation, crew training materials, and service models that reduce downtime and support electronic record-keeping. Consider modular architectures that allow configuration adjustments as requirements evolve. Strengthen regional service presence where retrofit and newbuild activity is concentrated, since responsiveness and parts availability increasingly influence purchasing decisions.
For Investors Evaluating Exposure
Assess exposure through the lens of total cost of ownership rather than unit pricing, with attention to service attach rates, consumable economics, and the breadth of certification and approval status across key regions. Differentiate between players with broad marine system integration capabilities and those with focused technology strengths. Monitor regulatory developments that could shift demand timing or favor particular treatment approaches, and weigh the resilience of service networks against the risk of regional inspection variability.
For Shipowners and Procurement Teams
Prioritize solutions that match the vessel’s operating profile, expected water quality variability, and inspection exposure, while keeping total cost of ownership at the center of evaluation. Favor systems that simplify maintenance, integrate with existing control and reporting workflows, and provide clear documentation support. Plan retrofit campaigns with dry-dock scheduling and service availability in mind, and seek configurations that can adapt to potential regulatory updates without major rework.
In all cases, the strategic value of detailed, up-to-date market intelligence is substantial. Segment-level demand patterns, regional inspection nuances, and technology-specific performance considerations can materially affect procurement timing and product selection. Access to granular data and tailored scenarios helps decision-makers move from broad trends to specific, defensible choices. PW Consulting’s in-depth research on the ballast water treatment equipment market provides that layer of detail, offering segmented analysis and customized viewpoints to support planning with greater precision.
For detailed analysis of this topic, please visit the official page: Ballast Water Treatment Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
UV Light Disinfection Market 2026: Why 15.4% CAGR Signals Strategic Shifts Beyond Water Treatment
By pmarketresearch, 2026-09-21
The UV Light Disinfection Market: Strategic Trends and Commercial Opportunities Through 2032
The UV light disinfection market has moved from a niche operational consideration to a central pillar of public health, infrastructure resilience, and facility safety strategies. Over the historical period from 2020 to 2025, the industry demonstrated consistent expansion, with the global market reaching approximately USD 387.0 million by the base year of 2025. Forward projections indicate sustained momentum, with the market expected to grow at a compound annual growth rate of 15.4 percent through the forecast period ending in 2032, ultimately approaching a valuation near USD 1,055.0 million. This trajectory reflects more than cyclical demand recovery; it signals a structural reorientation in how organizations approach microbial risk, regulatory compliance, and operational efficiency.
The scale and pace of this expansion carry meaningful implications for strategic decision-makers. A mid-teens CAGR across a seven-year horizon suggests that UV disinfection is transitioning from reactive procurement to embedded capital planning. The acceleration is not uniform across all use cases or geographies, and the concentration of revenue among a handful of established players indicates that competitive positioning will increasingly depend on regulatory clearance, application-specific validation, and total cost of ownership performance rather than standalone hardware specifications.
Market Snapshot and Structural Context
The market's expansion over the past half-decade has been characterized by broad-based adoption across water infrastructure, healthcare environments, and public-facing facilities. Revenue growth during the historical window reflects a combination of post-pandemic hygiene awareness, aging water treatment assets requiring modernization, and a growing acceptance of ultraviolet technology as a chemical-free or chemical-reducing intervention. The forecast period is expected to extend these dynamics while introducing new layers of complexity around device validation, reimbursement pathways, and cost-competitiveness against conventional alternatives.
A useful way to frame the market's current state is through its concentration profile. The sector remains moderately consolidated, with the top three participants capturing roughly 45 percent of revenue and the top five collectively accounting for approximately 55 percent. This level of concentration suggests that scale advantages, established distribution channels, and existing regulatory track records still matter, but it also leaves meaningful space for specialized entrants that can demonstrate superior performance in narrowly defined applications or high-value clinical workflows. The market is neither fully fragmented nor tightly monopolized, which creates a strategic environment where focused innovation can gain traction before larger players respond through acquisition or product line expansion.
UV Disinfection Equipment Market
Key Challenges and Inflection Points
Despite favorable demand signals, the industry faces several structural challenges that will shape which companies and applications succeed over the next decade. The first challenge revolves around validation and standardization. As UV disinfection moves into more regulated settings, buyers increasingly demand reproducible efficacy data under real-world operating conditions, not just laboratory benchmarks. Devices that cannot clearly demonstrate consistent microbial reduction across variable surface geometries, airflow patterns, or water turbidity profiles will face growing scrutiny from procurement teams and clinical stakeholders.
A second challenge lies in balancing capital expenditure against lifecycle economics. While ultraviolet systems can reduce ongoing chemical handling, manual cleaning labor, and infection-related costs, the upfront investment and replacement cycle for lamps, sleeves, and controller units remain important considerations. Organizations with constrained capital budgets need transparent payback logic, and suppliers must be able to articulate how equipment longevity, energy consumption, and maintenance intervals translate into measurable operational savings. The market is shifting from a purchase-of-equipment mindset to an evaluation of total intervention cost, which raises the bar for commercial messaging and economic modeling.
A third challenge is the growing complexity of regulatory expectations. Health authorities and standards bodies are refining how UV devices should be tested, documented, and integrated into existing infection control or water safety plans. This is a positive development for long-term credibility, but it introduces short-term friction for manufacturers that must navigate differing clearance pathways, regional normative references, and buyer-specific documentation requirements. Companies that treat regulatory engagement as a one-time event rather than an ongoing capability risk losing relevance as procurement criteria become more formalized.
These challenges are not simply obstacles; they are also the forces redefining competitive advantage. Suppliers that align product design, clinical or environmental validation, and economic documentation with the way end-users now make decisions will be better positioned to capture share in a market that is becoming more demanding, not just larger.
Drivers Reshaping the UV Disinfection Landscape
Technology Innovation and Application-Specific Engineering
The most durable driver of market expansion is the continued refinement of ultraviolet hardware and system architecture. Historically, generic lamp-based solutions addressed broad disinfection needs, but the market is increasingly rewarding designs engineered for specific environments and use cases. In healthcare and life sciences, for example, the ability to deliver validated microbial reduction across complex room geometries or sensitive instrumentation has become a key differentiator. Devices that combine targeted emitter configurations, consistent dosing control, and workflow-compatible form factors are gaining traction because they reduce the gap between laboratory performance and operational reliability.
A parallel innovation track is the evolution of UV-C LED systems and related component technologies. LED-based architectures offer advantages in form factor, directing options, and integration flexibility, which makes them attractive for applications where traditional lamps may be less practical. At the same time, capital expenditure payback periods for such systems have been evaluated in the range of about 2.5 to 3.5 years, supported by lamp lifetimes commonly spanning 10,000 to 20,000 hours. These parameters matter because they give facility and operations leaders a more concrete framework for comparing UV investments against alternatives, especially where labor intensity, chemical storage, or downtime are significant cost drivers.
The strategic implication is that innovation is no longer measured by brightness or output alone. It is increasingly measured by how reliably a solution delivers repeatable disinfection in the context of real workflows, maintenance constraints, and energy budgets. Suppliers that develop modular platforms, adjustable dosing logic, and application-tailored validation packages are likely to outperform those offering one-size-fits-all hardware.
PW Consulting
Regulatory Momentum and Standards Development
Policy and regulatory dynamics are playing an increasingly decisive role in shaping demand. In healthcare and medical device contexts, clearance pathways and normative references have become essential prerequisites for adoption, not optional credentials. Recent industry activity illustrates how rapidly the environment is evolving. In early 2026, Xenex Disinfection Services achieved Health Canada registration for its LightStrike6 UV-C robot, extending its North American authorization footprint for healthcare use. Later in the same year, UV Smart Technologies B.V. secured FDA 510(k) clearance for its D60 UV-C system designed specifically for transesophageal echocardiography probe disinfection, marking a first for that application. Around the same period, Surfacide, LLC introduced its Helios+ UV-C system, which received FDA 510(k) clearance as a whole-room microbial reduction device using continuous 254 nm germicidal UV light.
These developments are significant because they show regulatory review moving toward more application-specific and workflow-specific scrutiny. Rather than treating ultraviolet disinfection as a single homogeneous category, agencies and advisory bodies are examining study designs, intended use cases, and device-specific risk profiles. This trend was reinforced by broader engagement from the FDA General Hospital and Personal Use Devices Panel Advisory Committee, which convened in late 2025 to discuss study design considerations for germicidal UV devices intended to help reduce healthcare-associated infections. At the same time, regional standards activity such as the Netherlands' NEN 8281:2025 framework for validating UV-C disinfection of non-critical and semi-critical medical devices signals that structured validation expectations are becoming more explicit across parts of Europe as well.
For market participants, the implication is clear: regulatory engagement is no longer a downstream compliance task. It is a central element of product strategy. Companies that invest early in well-designed clinical or environmental evidence, that understand the difference between clearance types and their commercial consequences, and that can map their devices to applicable standards will gain meaningful purchase over competitors that rely solely on generic performance claims.
Demand-Side Shifts in Healthcare, Water, and Public Infrastructure
Demand is being reshaped not only by regulation but also by changing organizational priorities. In healthcare, the emphasis on reducing healthcare-associated infections continues to drive interest in complementary disinfection layers that can support, rather than replace, existing hygiene and cleaning protocols. UV-based interventions are increasingly evaluated against practical economic benchmarks, including the total cost of environmental control per bed or per procedure area. Publicly available comparisons have suggested that UV-C sanitization devices can present a median cost profile of roughly AUD 360 per bed per year, compared with approximately AUD 965 associated with hand hygiene protocols in some analyses. While such figures must be interpreted in context and vary by setting, they illustrate a broader point: procurement teams are looking for solutions that fit within cost-constrained infection prevention programs and offer quantifiable operational trade-offs.
In water and wastewater applications, demand is being driven by the need to modernize aging infrastructure, meet stricter effluent and drinking water quality expectations, and reduce chemical handling in treatment workflows. Municipal and industrial operators are evaluating UV systems not only for pathogen control but also for integration with existing treatment trains, energy constraints, and lifecycle maintenance plans. This creates a market environment where success depends less on the novelty of the concept and more on service reliability, dosing consistency, and the ability to support large-scale operational continuity.
Across both clinical and infrastructure settings, the common theme is a shift from awareness to evaluation. Buyers are not simply asking whether UV disinfection works in principle; they are asking which configuration works best in their environment, how it interacts with current processes, and what the real total cost of ownership looks like over multiple years.
Supply Chain, Component Economics, and Total Cost Positioning
Cost structure and supply chain resilience are becoming more visible as decision factors. The UV disinfection market spans lamps, reactor chambers, quartz sleeves, controller units, and a range of ancillary components, each with its own replacement cadence, sourcing complexity, and performance sensitivity. Fluctuations in raw material availability, electronics supply, and specialized glass or quartz components can affect product lead times and cost stability, particularly for manufacturers that depend on tightly integrated component chains.
At the same time, the market is seeing growing attention to design choices that reduce long-term operating burden. Longer service life for light sources, robust controller electronics, and serviceable chamber or sleeve designs all contribute to total cost positioning in ways that matter to buyers. The strategic relevance of this driver is that competitiveness increasingly depends on engineering for maintainability and cost transparency, not just peak disinfection output. Suppliers that can document predictable maintenance intervals, spare part availability, and energy usage patterns are better equipped to defend their pricing and build trust in sectors where downtime or compliance failures carry substantial consequences.
Competitive Positioning in a Maturing Market
The landscape of leading participants reflects the market's dual character: it contains broad-platform vendors serving large utility and industrial segments, as well as specialized players targeting high-value, regulation-sensitive applications. Firms such as Xylem Inc. and Trojan Technologies Group ULC have long been associated with UV disinfection systems for water and wastewater treatment, where scale, reliability, and integration with treatment infrastructure are paramount. Their strategic positioning tends to center on proven performance in demanding continuous-operation environments, supported by service networks and a focus on municipal and industrial procurement cycles.
Halma PLC and Atlantic Ultraviolet Corporation represent additional depth in UV equipment and product portfolios that span air and water applications, often with an emphasis on established distribution, component reliability, and broad market coverage. OSRAM GmbH and Heraeus Holding GmbH contribute important upstream and component-oriented capabilities, particularly around UV lamps and related equipment, reinforcing a supply base that is crucial for downstream system performance and availability. Koninklijke Philips N.V. has extended its presence into UV-C systems and air purification solutions, leveraging a position that intersects consumer-adjacent, clinical, and environmental health requirements.
At the same time, the market is being shaped by companies that compete through application specificity and regulatory differentiation. Xenex Disinfection Services has built its profile around UV-C whole-room microbial reduction robots, with recent North American authorization milestones reinforcing its positioning in healthcare settings. Surfacide, LLC has emphasized continuous 254 nm germicidal UV light for whole-room microbial reduction with FDA 510(k) cleared devices, distinguishing its approach through emitter configuration and clearance status. UV Smart Technologies B.V. has focused on UV-C high-level disinfection systems, including devices for transesophageal echocardiography probes, targeting specialized clinical workflows where application-specific clearance creates meaningful barriers to comparison. PuraCath Medical similarly targets a narrow but consequential need through UV disinfection systems for needleless connectors intended to reduce central line-associated bloodstream infections.
These distinctions matter because they reveal how competitive advantage is being redefined. The market is not simply moving toward consolidation through scale; it is also fragmenting into high-value niches where regulatory clearance, intended-use specificity, and workflow fit determine commercial value. Some of the strongest opportunities are emerging where a solution can demonstrate a defensible claim in a tightly defined use case, then expand from there through adjacent applications or geographic rollout.
Strategic Differentiation and Market Evolution
Looking across the leading set, several strategic postures emerge. One approach is platform breadth: supplying a wide range of UV products and services across water, air, and surface applications, with competitive advantage rooted in reliability, service coverage, and existing customer relationships. A second approach is clinical or procedural specificity: developing devices that address a particular disinfection workflow, often supported by targeted regulatory clearances and evidence packages. A third approach is component or upstream strength, where leadership in lamps, optics, or material performance underpins downstream system competitiveness.
The market is likely to see continued evolution along both consolidating and differentiating lines. Larger integrators may pursue acquisitions or internal platform expansion to cover more applications and geographies, especially where water infrastructure or broad facility management portfolios are concerned. At the same time, smaller or mid-sized innovators may capture premium positioning by solving validation, usability, or workflow-integration problems that broader competitors have not prioritized. New entrants will find the most viable openings in areas where buyers face clear pain points, where standards are becoming explicit, and where the economics of chemical reduction or labor savings can be clearly quantified.
Importantly, the concentration structure of the market does not imply that innovation is throttled by incumbency. Because the top three firms capture less than half of revenue, there is room for specialized devices, regional champions, and application-first strategies to gain momentum before the landscape fully stabilizes. This creates a strategic window for organizations that can move quickly on evidence generation, regulatory alignment, and operational proof points.
Forward Trends Shaping the Next Three to Five Years
From General Efficacy to Validated, Application-Specific Deployment
One of the most important trends expected to intensify through the forecast period is the shift from broad efficacy claims to validated, application-specific deployment. Buyers in healthcare, food and beverage, and water treatment are increasingly looking for documentation that matches their operational context. This means devices will need to show not only that they can achieve microbial reduction in principle, but also that they do so consistently under defined use conditions, with traceable testing, and within a workflow that staff can realistically sustain.
This trend will likely reward suppliers that invest in structured validation programs, that design for repeatable dosing, and that can communicate performance in operationally relevant terms. It also creates an opportunity for differentiation around service and support, since a UV system that is validated but difficult to maintain will lose its advantage over time. Companies that build validation, training, and lifecycle support into the core offering are better positioned to convert early adoption into durable deployment.
Integration of UV Systems into Broader Environmental and Water Safety Strategies
Another trend is the growing integration of UV disinfection into broader environmental health, water safety, and facility operations planning. Rather than treating ultraviolet systems as standalone interventions, organizations are increasingly considering how they fit alongside chemical treatment, filtration, ventilation, and hygiene protocols. This integration mindset favors solutions that can be monitored, controlled, and maintained within existing operational frameworks, and it encourages the use of UV technology where it can reduce chemical handling, simplify compliance, or improve resilience in continuous-use environments.
Commercial opportunities here include bundled service models, remote monitoring or performance reporting, and flexible system architectures that adapt to changing throughput or regulatory requirements. In water and wastewater contexts, in particular, the next several years are likely to see continued demand for systems that balance pathogen control with energy efficiency, maintenance predictability, and integration into large-scale treatment operations.
Cost Discipline, Lifecycle Economics, and Financing-Sensitive Procurement
A third trend is the increasing weight of lifecycle economics in procurement decisions. As organizations compare UV solutions against conventional cleaning, chemical treatment, or alternative disinfection technologies, they are focusing more closely on payback, replacement cycles, energy consumption, and labor impacts. The trend is especially relevant where capital budgets are constrained or where infection-related costs, chemical compliance, or facility downtime create strong incentives to justify investment with transparent economic logic.
This trend encourages two strategic responses. For manufacturers, it raises the importance of credible total cost of ownership narratives and long-life component design. For buyers, it creates an opportunity to move beyond price-per-unit comparisons and toward evaluations that capture operational savings, compliance risk reduction, and service continuity. The organizations that can quantify these elements effectively will have an advantage in both selling and buying decisions.
Potential Risks and Uncertainties
Several uncertainties could shape the trajectory of the market. Regulatory expectations may continue to tighten or diverge across regions, which would reward companies with strong documentation capabilities while pressuring those that rely on generalized claims. Economic volatility and capital expenditure constraints could slow adoption in some segments, particularly where buyers must prioritize competing infrastructure needs. There is also the risk that underperforming or poorly validated devices could damage trust in specific application categories, making the quality of evidence and service support even more important across the board. Finally, component supply dynamics and lamp or LED replacement cycles remain operational realities that can affect margins and customer satisfaction if not managed carefully.
These risks do not undermine the market's fundamental direction, but they do suggest that success will depend on disciplined execution: clear claims, strong validation, operational reliability, and credible cost modeling.
Actionable Implications for Decision-Makers
For Manufacturers and Technology Providers
Focus on application-specific value rather than generic disinfection messaging. The competitive edge in the next phase will likely belong to companies that can match device capabilities to well-defined workflows, support them with credible evidence, and document total cost of ownership including maintenance, replacement, and energy considerations. Regulatory engagement should be treated as a strategic capability, not a compliance afterthought, especially as clearance pathways become more application-aware and expectations around study design and validation become more structured.
In practical terms, this means prioritizing the development of validation packages that reflect how customers actually use devices, building serviceable and durable system architectures, and preparing for a landscape where procurement decisions are increasingly influenced by lifecycle economics and regional standards alignment. Companies that can demonstrate consistent performance in the exact context where they are sold will have stronger positioning than those that rely on broad but less differentiated claims.
For Investors
Pay attention to where regulatory clearance, application specificity, and documented cost advantages intersect. The market is large enough to support both scaled platforms and focused innovators, but the most durable returns are likely to come from businesses that can defend a clear intended-use niche while building evidence and service capabilities that make adoption repeatable. In water and wastewater, scale, reliability, and integration strength remain central; in healthcare and specialized surface or instrument disinfection, clearance status and workflow fit can create higher barriers to comparison and stronger pricing power.
Investors should also weigh supply chain exposure and component lifecycle economics, since lamp life, controller durability, and replacement part availability can materially affect both commercial margins and end-user satisfaction. A disciplined approach to assessing evidence quality, regulatory status, and operational economics will be more useful than broad assumptions about market growth alone.
UV Infection Control Device Market
For Procurement and Operations Leaders
Evaluate UV disinfection as part of a broader risk-reduction and operational efficiency strategy, not as a single-point purchase. Ask for evidence that reflects your actual operating conditions, clarify the total cost of ownership over the equipment's service life, and consider how the system will integrate with existing cleaning, treatment, ventilation, or infection prevention workflows. Where possible, prioritize solutions that provide transparent maintenance expectations, service support, and performance documentation that can be reviewed by clinical, environmental, or compliance stakeholders.
In water and wastewater contexts, emphasize reliability, energy and maintenance implications, and integration with existing treatment processes. In healthcare and public-facing settings, give appropriate weight to clearance status, validation methodology, and the practical realities of staff workflow. The organizations that make decisions on this basis are more likely to realize the intended benefits without encountering hidden operational friction.
For decision-makers who need to move quickly across multiple segments, regions, or application categories, the most efficient next step is to anchor strategy in a structured market view that connects macro growth trajectories with the specific segment dynamics, regulatory milestones, and competitive distinctions shaping adoption today. A detailed reference point that consolidates these dimensions can help teams compare opportunities, prioritize validation and procurement pathways, and identify where further due diligence is required. Readers seeking a fuller breakdown of segment-level dynamics, regional variation, and targeted commercial scenarios can explore the complete PW Consulting market analysis for additional depth and customized guidance.
For detailed analysis of this topic, please visit the official page: UV Light Disinfection Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Refractories Market 2026: Why 5.7% CAGR and Asia Pacific’s Scale Redefine Strategy
By pmarketresearch, 2026-09-21
Strategic Shifts and Commercial Opportunities in the Refractories Market
Navigating a Sector at the Intersection of Industrial Demand and Sustainability Imperatives
The global refractories market is entering a phase of measured expansion, underpinned by steady industrial activity and a gradual shift toward higher-performance, environmentally compliant materials. With total market revenue reaching approximately USD 359.4 million in the base year of 2025, the sector has recovered from earlier cyclical slowdowns and now reflects a compound annual growth rate of 5.7 percent across the historical window spanning 2020 through 2025. Projections for the forecast period extending from 2026 through 2032 indicate continued upward momentum, with revenue expected to climb steadily toward USD 522.49 million by 2032. This trajectory suggests that the industry is not merely rebounding to pre-downturn levels, but is absorbing structural changes in end-user requirements, material science advancements, and supply chain reconfiguration.
The market scale observed in 2024, at USD 336.06 million, already reflected a meaningful acceleration from the 2023 baseline of USD 325.58 million, signaling that industrial infrastructure upgrades, capacity restorations in select regions, and sustained throughput in metals and construction-linked industries are translating into firmer demand for high-temperature containment solutions. As the sector moves deeper into the forecast horizon, the growth narrative will increasingly be shaped by how companies navigate material sourcing constraints, regulatory pressure on carbon intensity, and the competitive dynamics of a concentrated industry where the top three players collectively account for roughly 40 percent of revenue and the top five capture approximately 45 percent. These concentration figures point to a market where scale, technological differentiation, and regional reach remain decisive, yet they also leave meaningful room for specialized entrants and regional specialists to capture value in niche applications and localized supply ecosystems.
Worldwide Refractory Anchor Market
For executives and investors, the immediate takeaway is that the refractories sector is no longer a commodity-like volume play. Instead, it is evolving into a performance-driven, compliance-sensitive segment where margin resilience depends on product innovation, supply chain agility, and the ability to align with downstream decarbonization roadmaps. The following sections unpack the core challenges, demand drivers, competitive moves, and forward-looking trends that will define strategy in this market over the next several years.
Market Snapshot: Scale, Trajectory, and Structural Signals
The revenue progression from 2020 through 2025 illustrates a market that has navigated external disruptions while maintaining a positive growth arc. After a base of USD 282.66 million in 2020, the industry recorded sequential gains that culminated in the 2025 figure of USD 359.4 million. This upward slope reflects more than simple recovery; it suggests shifting procurement patterns, a gradual premiumization trend toward products capable of withstanding higher thermal and chemical stress, and durable utilization rates in core industrial segments. The forecast path continues this direction, with revenue expected to rise through 2032, ending at USD 522.49 million. The compound annual growth rate of 5.7 percent across the full 2020 to 2032 horizon implies that growth will be consistent rather than explosive, emphasizing the importance of operational efficiency, product mix optimization, and regional execution over sheer volume expansion.
A notable characteristic of the current landscape is the dominance of Asia Pacific in overall market revenue, which underscores the region’s role as the primary engine of industrial throughput and refractory consumption. At the same time, the presence of meaningful revenue bases in other regions indicates that demand is not monolithic. Different geographies are responding to distinct infrastructure cycles, regulatory environments, and industrial composition, which means global players must tailor their go-to-market strategies rather than rely on a uniform expansion model. The concentration profile of the market further reinforces the strategic importance of differentiation. In a sector where top-tier firms hold a substantial share of total revenue, competitive advantage increasingly derives from specialized material formulations, application engineering, service layering, and supply reliability rather than price competition alone.
Critical Challenges and Inflection Points
One of the most pressing challenges shaping the refractories market is the tension between performance requirements and sustainability mandates. End-users in steel, cement, glass, and non-ferrous metals are under intensifying pressure to reduce operational emissions, which in turn places expectations on refractory suppliers to deliver materials that support energy-efficient processes and lower thermal losses. This demand is not purely aspirational; it is increasingly codified in procurement standards, customer sustainability targets, and in some cases, regulatory frameworks. Companies that cannot demonstrate credible pathways toward lower-carbon products, responsible raw material sourcing, and reduced waste generation risk losing relevance in bids where lifecycle and environmental criteria carry growing weight alongside traditional technical specifications.
A second challenge lies in the fragility and concentration of certain raw material supply chains. The dependence on specific mineral inputs, combined with geopolitical developments and trade policy shifts, creates exposure for manufacturers and end-users alike. Tariff adjustments, import flow variability, and sourcing disruptions can affect input costs and lead times, forcing producers to balance cost control with continuity of supply. This environment favors organizations that diversify sourcing options, invest in alternative material formulations, and maintain transparent supplier risk monitoring. Where input volatility persists, the ability to secure consistent quality at stable costs becomes a competitive differentiator as much as a procurement necessity.
A third inflection point is the accelerating pace of competitive consolidation and capability expansion. Recent corporate activity indicates that leading firms are actively pursuing scale, capacity additions, targeted acquisitions, and capability investments aimed at strengthening their positions in high-value product categories. This behavior signals that the market is moving toward a structure where adjacency expansion, technology-enabled product development, and localized manufacturing presence are used to deepen customer relationships and defend share. For smaller or regionally focused players, the challenge will be to identify defensible niches, whether through application specialization, technical service depth, or regional responsiveness, rather than competing directly on broad commodity fronts.
Core Demand Drivers Reshaping the Market
Technology Innovation and Material Performance Gains
Advancements in material science and application engineering are reshaping what refractories can deliver in demanding operating environments. The industry is seeing a greater emphasis on formulations that extend service life, reduce maintenance frequency, and improve thermal stability under severe mechanical and chemical stress. Investments in research, including collaborations that integrate advanced modeling and artificial intelligence into material development, are shortening development cycles and enabling more precise tailoring of products to specific process conditions. These capabilities matter because refractory replacement cycles directly affect throughput, downtime, and operating costs for end-users. A product that performs longer and fail more predictably can create measurable value beyond its unit price, which shifts purchasing decisions toward total cost of ownership and reliability rather than initial cost alone.
Recent developments in the sector demonstrate how innovation is being operationalized. One Japanese manufacturer announced a strategic partnership with a leading technology firm in mid-2025 to develop advanced refractory materials using artificial intelligence, signaling a broader interest in data-driven formulation optimization. At the same time, U.S.-based firms have expanded capacity in critical product categories; for example, a major monolithic refractory producer acquired a facility in Ohio during mid-2025 to expand its production footprint for precast and monolithic solutions. These moves illustrate that innovation is not limited to laboratory-level breakthroughs. It also includes manufacturing footprint decisions that improve responsiveness, reduce logistics friction, and support higher-value product lines where application engineering and repeatability are key.
Policy, Regulation, and Environmental Compliance
Regulatory and policy dynamics are increasingly shaping both input availability and product design priorities. In the United States, trade-related adjustments have influenced the flow and cost of certain minerals used in refractories production. Tariff increases on specific imported materials, alongside temporary exemptions and procedural extensions, have introduced uncertainty into sourcing strategies and encouraged suppliers to reassess exposure to single-origin dependencies. These developments matter because refractory manufacturers rely on a range of mineral inputs whose availability and pricing can directly affect margins and delivery reliability. The practical response from progressive suppliers and buyers alike has been to strengthen supply chain visibility, evaluate substitution pathways, and incorporate compliance considerations into product development from the outset rather than treating them as afterthoughts.
On the product side, environmental compliance is moving from a constraint to a strategic lever. The incorporation of recycled materials into certain brick formulations, while maintaining regulatory limits on contaminants such as chromium, reflects an emerging capacity to reconcile sustainability goals with performance requirements. This type of progress is significant because it demonstrates that compliance-driven material changes can be implemented without abandoning technical integrity. As industrial customers align procurement with decarbonization objectives, suppliers that can document lower environmental impact, responsible sourcing, and measurable performance under real operating conditions will be better positioned to win preference in competitive evaluations.
Demand-Side Evolution in Core Industrial Segments
Demand for refractories remains closely tied to the operating intensity of heavy industrial sectors, especially iron and steel, where thermal containment and wear resistance are fundamental to continuous production. Beyond primary metals, applications in cement, glass, and non-ferrous processing continue to contribute meaningful revenue, each with distinct technical requirements and procurement rhythms. What is changing is the emphasis on lifecycle value and process efficiency. End-users are increasingly interested in solutions that reduce energy loss, withstand longer campaign lengths, and support stable operations in environments where downtime is expensive and process variability carries direct financial consequences.
Refractory Bricks Market
This demand-side evolution is also visible in the way customers evaluate suppliers. Technical capability, application support, and delivery consistency are gaining relative importance alongside price. In many procurement environments, the decision is no longer a simple choice among comparable products; it is a selection among differentiated offerings that vary in formulation quality, installation support, service responsiveness, and regional supply reliability. For refractory producers, this means that value creation depends on being able to demonstrate how a given solution contributes to the customer’s operational and sustainability goals. For buyers, it means that supplier evaluation frameworks should account for total operating impact rather than unit price in isolation.
Supply Chain Reconfiguration and Cost Structure Pressures
Cost structures in the refractories sector are being influenced by a combination of raw material volatility, energy exposure, logistics complexity, and the strategic need to localize production in response to customer expectations and trade dynamics. Some input markets have experienced disruptions that reduced import volumes and forced procurement teams to adjust sourcing plans, while trade policy changes have altered the relative attractiveness of different supply routes. These conditions are encouraging a broader reassessment of how refractory companies structure their upstream dependencies and downstream delivery networks.
At the same time, expansion into new manufacturing locations is becoming a strategic response to demand geography and supply risk. A notable example is the establishment of a new manufacturing facility in Vietnam by a major engineered ceramics and metal flow solutions provider in mid-2025, reflecting a deliberate effort to strengthen regional capacity and align production more closely with demand centers in Asia. This kind of location strategy can improve lead times, reduce freight exposure, and enhance the ability to serve customers with region-specific requirements. For the broader market, it suggests that competitive positioning will increasingly depend on where capacity is located, how flexibly it can be reconfigured, and whether suppliers can maintain cost discipline while meeting higher service expectations.
Competitive Landscape and Strategic Positioning
The refractories market is characterized by a group of established international players with strong application expertise, global distribution reach, and growing emphasis on differentiated product portfolios. In high-grade refractory products and systems, a Vienna-based leader remains prominent across steel, cement, glass, and non-ferrous metals, with a profile built on breadth of offering and industrialapplication depth. A London-headquartered provider has strengthened its relevance through engineered ceramics and metal flow solutions, particularly in steelmaking and foundry contexts where flow control and thermal performance intersect. A Paris-based specialist continues to focus on high-performance ceramics and refractories for extreme-temperature applications, emphasizing the performance envelope required in the most demanding process environments.
Asian manufacturers also play a significant role. A Tokyo-based producer is recognized for high-quality refractory bricks, monolithics, and functional products used in blast furnace, casting, and kiln applications, while another Japanese firm maintains a strong presence in high-quality bricks and materials for the iron and steel industry. In India, a Kolkata-headquartered specialist provides refractory solutions tailored to iron-steel and foundry requirements, reflecting the importance of regional application knowledge and customer proximity. In the United States, a Columbus-based company is known as a global leader in monolithic refractory ceramics and precast shapes, with an emphasis on solutions that support faster installation, repeatability, and reduced downtime.
These profiles point to several patterns in strategic positioning. First, market leaders are building advantage not just through scale, but through application-specific expertise, service integration, and the ability to support complex customer requirements across multiple industries. Second, differentiation is increasingly tied to product performance under severe conditions, installation efficiency, and the use of advanced development methods that accelerate formulation refinement. Third, regional expansion and targeted capacity additions are being used to strengthen responsiveness and reduce exposure to long supply chains. Rather than treating refractories as a standardized product category, leading players are advancing it as a solutions space where technical reliability, delivery assurance, and evolving environmental performance all contribute to competitive advantage.
Market Evolution and Structural Trends
One clear trend in the competitive landscape is selective consolidation and capability deepening. Recent activity includes capacity-expanding acquisitions, new product introductions aimed at reducing carbon emissions in industrial processes, and partnerships that bring advanced analytical methods into material development. An acquisition completed in the United States during mid-2025 expanded monolithic refractory production capacity, reinforcing a broader industry emphasis on precast and monolithic solutions that can improve installation speed and consistency. A product launch later in the year introduced a new line of eco-friendly refractory products designed to reduce carbon emissions in industrial processes, highlighting how environmental performance is becoming a stated product strategy rather than a side initiative.
At the same time, market structure is evolving through facility expansion in strategically relevant geographies and technology-linked partnerships that aim to raise the bar on material performance. These moves suggest a market in which incumbents are reinforcing their positions while also seeking new avenues for differentiation. For newer or smaller players, the likely path to relevance lies in specialization: targeted applications, regional service advantages, formulation expertise in specific material families, or superior responsiveness in supply chains where reliability is highly valued. The presence of both global scale players and regionally embedded specialists indicates that the market will remain pluralistic, but competition will increasingly reward those who can combine technical credibility with operational dependability.
PW Consulting
Outlook: Three Trends to Watch Over the Next Three to Five Years
The first trend is the continued alignment of refractory development with downstream decarbonization goals. As industrial operators set targets for energy efficiency and emissions reduction, refractory suppliers will face greater expectation to offer products that help lower thermal losses, extend campaign life, and support cleaner process designs. Commercial opportunity will accrue to companies that can substantiate performance claims, provide transparent environmental data, and integrate compliance considerations into product architecture. The associated risk is that sustainability expectations may outpace the technical feasibility of certain material substitutions, creating tension between customer ambitions and achievable performance.
The second trend is the growing importance of supply chain resilience and input diversification. Trade policy changes, import flow variability, and mineral sourcing dependencies are likely to keep pressure on procurement strategies. Companies that broaden their supplier base, qualify alternative materials where feasible, and maintain visibility into geopolitical and logistics risks will be better positioned to protect margins and delivery reliability. The opportunity here is to turn supply chain rigor into customer trust, especially in markets where continuity of supply and predictable lead times are valued as part of the overall solution. The risk is that rapid shifts in trade rules or unexpected disruptions can still affect costs and availability, particularly for specialized inputs with limited substitution options.
The third trend is the shift from product selling toward solutions-oriented engagement. This includes greater emphasis on application engineering, installation support, lifecycle assessment, and performance monitoring. As end-users prioritize operational stability and total cost of ownership, suppliers that can provide integrated support across the product lifecycle will gain stronger positioning. The commercial opportunity lies in service differentiation and customer lock-in through technical value rather than price competition. The risk is that service commitments increase exposure to performance variability and require disciplined execution across regions, especially where local capabilities and skilled labor availability differ.
Implications and Strategic Actions for Decision-Makers
For refractory manufacturers, the priority is to strengthen product differentiation while managing input and compliance risk. This means investing in formulations and development methods that improve durability and thermal performance, documenting sustainability attributes in ways that withstand procurement scrutiny, and aligning capacity decisions with demand geography and service expectations. Manufacturers should also assess where monolithic, precast, or specialized brick solutions can deliver measurable advantages in installation speed, repeatability, and lifecycle cost, and structure their portfolios accordingly. Where raw material exposure is concentrated, diversifying sourcing and qualifying alternatives should be treated as strategic actions rather than purely procurement tasks.
For investors, the relevant question is where value creation is most durable. Markets with steady industrial demand and growing emphasis on performance, reliability, and environmental compliance are likely to reward companies with strong application expertise, clear product differentiation, and disciplined execution in regional expansion. Due diligence should pay attention to raw material exposure, supply chain geography, and the credibility of sustainability claims, since these factors increasingly influence competitive positioning and margin resilience. Investment theses should also consider whether a company is competing on scale alone or has defensible advantages in formulation, service, or regional responsiveness, because those distinctions often determine long-term share dynamics in concentrated markets.
For procurement and industrial buyers, the opportunity is to move beyond unit-price comparisons and incorporate total cost of ownership, campaign life, installation efficiency, and environmental performance into supplier evaluation. In environments where downtime is expensive and process stability is critical, a refractory solution that reduces maintenance frequency or extends service intervals can generate value that is not visible in the initial purchase price. Buyers should also evaluate supplier risk on inputs and logistics, since continuity of supply can be as important as technical specifications. Where possible, procurement frameworks should include documentation of material origin, recycled content where applicable, and compliance with relevant environmental limits, so that purchasing decisions align with operational and sustainability requirements.
For all stakeholders, the strategic implication is that timely, granular intelligence matters. Market direction is visible at the aggregate level, but the real decisions—where to expand capacity, which formulations to prioritize, how to manage input exposure, and how to respond to competitor moves—require detailed segmentation, regional nuance, and a clear view of competitor activity. Detailed research that breaks down performance by application requirements, material families, regional demand patterns, and competitive maneuvers can help decision-makers move from general awareness to specific action.
Deepening the Strategy Conversation
The refractories market is not simply expanding; it is being reshaped by the intersection of industrial demand, material innovation, supply chain realignment, and sustainability expectations. That combination creates opportunities for suppliers that can deliver superior performance and credible compliance, for investors that can identify durable competitive advantages, and for buyers that can align procurement with total operational value. At the same time, the sector remains exposed to input volatility, trade policy shifts, and the execution challenges that accompany product and capacity strategy changes. In this environment, clarity on segmentation, regional dynamics, and competitive behavior is essential for confident decision-making. More detailed data, application-level breakdowns, and company-specific developments are available in the full research report, which provides the depth needed to turn these strategic themes into concrete plans.
For detailed analysis of this topic, please visit the official page: Refractories Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hydrogen Sulfide Scavengers Market: Inside the 3.44% CAGR Upside to 2032
By pmarketresearch, 2026-09-21
The Hydrogen Sulfide Scavengers Market: Navigating Growth, Regulation, and Chemical Innovation
Hydrogen sulfide remains one of the most persistent operational and safety hazards across oil and gas production, gas processing, and wastewater treatment. The compounds corrosive nature, toxicity, and tendency to form metal sulfides make its control a non-negotiable requirement for compliant and efficient operations. Against this backdrop, the global market for hydrogen sulfide scavengers has settled into a measured but steady growth trajectory, expanding from approximately 305 million USD in 2020 to an estimated 370.5 million USD in 2025, with projections reaching roughly 472 million USD by 2032. The implied compound annual growth rate of 3.44 percent over the 2025 to 2032 forecast window reflects a market that is maturing rather than exploding, driven less by explosive volume demand and more by regulatory tightening, operational optimization, and incremental chemical innovation.
For executives and investors, the central takeaway is that this is not a high-growth novelty segment but a stable, regulation-anchored specialty chemicals market with meaningful margin potential for players who can differentiate on performance, safety, and total cost of ownership. The challenge lies in recognizing where the growth pockets are forming, which product architectures are gaining ground, and how leading suppliers are repositioning themselves in a landscape marked by fragmented demand, supply chain friction, and increasingly stringent emission controls.
Market Structure and Core Challenges
The market's evolution over the 2020 to 2025 period tells a story of resilience amid volatility. Revenue growth from 305.21 million USD in 2020 to 347.92 million USD in 2023, followed by a modest contraction to 346.36 million USD in 2024 before rebounding to 370.5 million USD in 2025, underscores how external shocks can temporarily disrupt even essential chemical supply chains. That 2024 dip, while relatively small in percentage terms, signals the market's sensitivity to raw material availability and pricing, particularly for triazine-based formulations that dominate high-volume applications. The rebound in 2025 suggests that demand fundamentals remain intact and that operators are unwilling to delay H2S control investments given the safety and compliance stakes involved.
Several structural challenges define the current inflection point. First, raw material dependency and supply chain vulnerability continue to shape pricing dynamics and product availability. The market relies heavily on precursor chemicals such as ethylene oxide and related intermediates for triazine-based scavengers. A plant incident in 2023 triggered shortages and price increases for these formulations, a disruption that rippled through procurement cycles well into 2025. This fragility has forced operators and suppliers alike to reconsider single-source dependencies and to evaluate alternative chemistries that can reduce exposure to precursor volatility.
Second, regulatory fragmentation across regions creates a complex compliance environment. In the United States, the Toxic Substances Control Act and related EPA and OSHA mandates increase the compliance burden for facilities handling sour streams, while Bureau of Safety and Environmental Enforcement rules under 30 CFR 250.490 require operators on the U.S. Outer Continental Shelf to maintain H2S scavengers on facilities and deploy them upon detection. In Europe, Directive 2016/2284 sets emission limits that drive H2S control requirements across industrial applications. In the Middle East and Africa, GSO ISO 8819:2013 provides regional standards for H2S treatment processes. These overlapping requirements mean that a one-size-fits-all product strategy is rarely sufficient; suppliers must navigate differing thresholds, testing protocols, and documentation expectations across jurisdictions.
Third, the market must balance performance against cost and environmental considerations. Traditional triazine-based scavengers offer effective H2S removal but can generate sludge, introduce nitrogen-containing byproducts, and carry higher handling costs in certain applications. The industry is increasingly asking whether alternative chemistries can deliver comparable or superior performance with reduced waste, lower corrosion risk, or easier integration into existing processes. This tension between proven reliability and the desire for cleaner, more efficient solutions is reshaping product selection criteria at the operational level.
The Demand Side: Where Growth Is Concentrated
H2S scavenging demand is anchored by three core application areas: oil industry operations, gas industry processing, and wastewater treatment. These segments collectively represent the bulk of market volume, with oil and gas applications historically dominating due to the prevalence of sour production streams and the high cost of downtime or safety incidents when H2S is not adequately controlled. Gas processing facilities face similar pressures, particularly where sales gas must meet pipeline specifications that impose strict H2S limits. Wastewater treatment represents a growing adjacent demand source, where H2S control intersects with odor management, corrosion prevention, and regulatory compliance for industrial and municipal effluent handling.
What ties these applications together is not just the presence of H2S but the operational consequences of failing to manage it. In production environments, H2S contributes to sulfide stress cracking, iron sulfide scale formation, and equipment fouling, all of which increase maintenance costs and reduce throughput. In gas transmission, failure to meet pipeline specifications can result in rejected volumes, fines, or the need for costly downstream cleanup. In water systems, H2S generates odors, accelerates corrosion in concrete and metal infrastructure, and poses worker safety risks in confined spaces. These cost and risk drivers ensure that H2S scavenging remains a priority even in capital-constrained cycles, because the alternative is often more expensive in the long run.
The market segmentation by type reflects a meaningful split between regenerative and non-regenerative approaches. Non-regenerative scavengers, which react with H2S to form stable compounds that are then disposed of or treated downstream, account for a larger share of current demand. Regenerative systems, which capture and release H2S for subsequent processing or reuse, appeal in contexts where continuous treatment, waste minimization, or resource recovery is prioritized. The relative balance between these two architectures is not static; it shifts with application requirements, operating economics, and the availability of disposal or recycling pathways.
Key Drivers Shaping the Market
Several forces are converging to shape the next phase of market development. Understanding these drivers is essential for identifying where investment, product development, and commercial strategy should be directed.
Technological Innovation and Performance Differentiation
Product innovation is moving beyond generic H2S removal toward application-specific formulations that address multiple operational pain points simultaneously. Recent product introductions illustrate this trajectory. In June 2025, Clariant introduced SCAVTREAT 1173, a gas phase hydrogen sulfide scavenger, expanding its portfolio for gaseous streams. The following month, the company released SCAVTREAT 13964, an H2S scavenger based on glycol derivatives in organic solvents, signaling a push toward alternative chemical architectures that may offer advantages in selectivity, handling, or compatibility with specific process conditions. These releases reflect a broader industry pattern: suppliers are investing in targeted formulations rather than relying solely on established triazine platforms.
Baker Hughes has similarly emphasized performance validation and cost reduction through real-world case studies. In July 2025, the company published a case study demonstrating that its PETROSWEET H2S scavenger reduced H2S levels in sales gas by 60 percent, enabling the operator to meet pipeline specifications and increase production revenue. In May 2025, a separate case study highlighted how the same product cut treatment costs in multiple contact tower applications. These examples underscore a shift in how suppliers justify value: not merely by stating that a product removes H2S, but by quantifying the downstream impact on revenue, compliance, and operating expense.
SLB contributed its own performance narrative in June 2025, releasing a case study on subsea injection of a proprietary H2S scavenger that reduced schmoo deposits and significantly lowered cost. This application highlights the growing relevance of H2S control in subsea and offshore environments, where access constraints, safety considerations, and deposit management create unique challenges. The ability to inject scavengers subsea and achieve measurable deposit reduction points to a niche where specialized formulations and delivery methods can command premium positioning.
Regulatory Pressure as a Structural Demand Driver
Regulation is not merely a compliance checkbox; it is a persistent demand anchor that shapes procurement behavior, product specification, and geographic prioritization. The U.S. regulatory framework, encompassing TSCA and EPA/OSHA mandates, increases the baseline requirement for effective H2S control across production and processing facilities. BSEE rules add a layer of operational obligation for offshore facilities, making scavenger availability and deployment a regulatory expectation rather than an optional best practice. In Europe, emission limits under Directive 2016/2284 sustain demand for H2S control across industrial applications, while GSO ISO 8819:2013 provides a regional standard that influences procurement specifications in the Middle East and Africa.
Hydrogen Sulfide Removal Market
For suppliers, this regulatory patchwork creates both opportunity and complexity. Products that can demonstrate compliance with multiple regional standards, provide robust documentation, and offer consistent performance across varying H2S concentrations and flow conditions gain a competitive advantage. Conversely, suppliers that treat regulation as a secondary concern risk losing specification share to competitors who position their products explicitly around compliance assurance and audit readiness.
Supply Chain Realities and the Push for Alternatives
The 2023 plant incident that disrupted ethylene oxide and related precursor supplies exposed a structural vulnerability in the triazine-based scavenger supply chain. The resulting shortages and price increases in 2025 reinforced the need for diversification, whether through alternative chemistries, multi-source procurement, or reformulated products that reduce dependency on constrained intermediates. This dynamic is accelerating interest in non-triazine options, including nitrogen-free formulations and glycol-derivative-based scavengers, as operators and suppliers seek to insulate operations from single-point failures in the raw material chain.
Cost structure evolution is also influenced by the total cost of treatment, not just the price per unit of scavenger. Factors such as dosing efficiency, sludge generation, corrosion impact, handling requirements, and waste disposal costs all contribute to the economic equation. Products that reduce overall treatment burden, even at a higher unit price, can win on total cost of ownership. This is particularly relevant in applications where downtime, equipment damage, or compliance penalties carry heavy financial consequences.
Competitive Landscape and Strategic Positioning
The hydrogen sulfide scavengers market is moderately concentrated, with the top three companies holding approximately 27.5 percent of revenue and the top five reaching roughly 39.8 percent. This concentration level indicates a market where leading players command meaningful share but where a long tail of specialized and regional suppliers retains relevance, particularly in niche applications, local service requirements, and cost-sensitive segments. The presence of large energy service and chemical companies alongside focused specialty chemical firms creates a dynamic where competition plays out across multiple dimensions: technical performance, application expertise, regulatory support, supply reliability, and total cost of ownership.
Baker Hughes and SLB, both headquartered in Houston, represent the energy services end of the spectrum. Baker Hughes has built its offering around PETROSWEET and SULFIX H2S scavenger solutions targeting crude oil, intermediates, refined products, and processing systems. Its recent case study activity emphasizes measurable outcomes—H2S reduction to meet pipeline specs, treatment cost reductions in contact towers, and subsea deposit control—positioning its products around demonstrated operational value rather than chemistry alone. SLB's liquid H2S scavenger portfolio includes triazine and nitrogen-free options for sour production streams, corrosion control, and HSE hazard management. Its subsea case study reinforces a strategy centered on solving hard-to-reach, high-consequence applications where performance and safety integration are paramount.
Clariant, based in Muttenz, Switzerland, brings a specialty chemicals perspective through its SCAVTREAT line, which addresses hydrogen sulfide, iron sulfide, sulfide scale, and oxygen control in gases and liquids. The 2025 introductions of SCAVTREAT 1173 and SCAVTREAT 13964 illustrate a focus on expanding the application envelope and exploring alternative chemical bases, such as glycol derivatives in organic solvents. This approach positions Clariant as a player investing in formulation breadth and application flexibility, appealing to operators seeking tailored solutions for specific gas or liquid streams.
Merichem Company, also headquartered in Houston, occupies a distinct position with its regenerable H2S scavengers via LO-CAT and EcoTreat technologies for sour gas streams. Regenerable systems appeal where continuous treatment, waste reduction, or resource recovery economics justify the higher complexity and capital considerations. This positions Merichem in a segment where lifecycle economics and sustainability considerations can outweigh lower upfront simplicity.
Other notable participants include SUEZ in Paris, with chemical solutions for H2S removal in water treatment and industrial applications; NuGenTec in the United States, offering triazine-based and non-triazine formulations; Dorf-Ketal in Mundra, Gujarat, India, with its MAXSCAV line for refinery and petrochemical process chemicals; Halliburton in Houston, providing production chemicals and H2S treatment solutions for oil and gas operations; Arkema in Colombes, France, with specialty chemicals and solutions for H2S control; ChemTreat in Glen Allen, Virginia, focusing on water treatment chemicals including H2S scavengers; Caradan Chemicals International in the United States, with H2S scavenger products for oil and gas applications; Paqell in the Netherlands, offering chemical solutions for H2S scavenging in industrial settings; and Nalco Water in Naperville, Illinois, with water treatment and H2S control products. This breadth of participants reflects a market where application specialization, regional presence, and service capabilities often matter as much as chemistry alone.
The competitive landscape is evolving along several axes. Consolidation pressure exists, particularly as larger energy service and chemical companies seek to strengthen their production chemicals portfolios and capture cross-selling opportunities across drilling, completion, production, and processing services. At the same time, fragmentation persists because H2S scavenging requirements vary widely by geography, application, H2S concentration, flow conditions, and regulatory context. New entrants and regional specialists can find room by focusing on underserved applications, localized service, or alternative chemistries that address specific pain points such as nitrogen-free requirements, reduced sludge generation, or improved compatibility with particular process environments.
Forward Trends and Commercial Implications
Looking ahead to the 2026 to 2032 window, several trends are likely to shape market direction and commercial opportunity.
PW Consulting Automotive & Machinery Research Center
Trend One: Performance Validation Becomes a Competitive Mandate
As operators face tighter margins and heightened compliance scrutiny, the ability to quantify the impact of H2S scavenging on revenue protection, cost reduction, and safety outcomes will increasingly differentiate suppliers. Case studies, field data, and application-specific performance benchmarks will move from marketing support to core competitive assets. Suppliers that invest in rigorous validation, transparent reporting, and customer-specific economic modeling will be better positioned to defend specification share and justify premium positioning. For buyers, this trend means that product selection will increasingly hinge on demonstrated outcomes in comparable applications rather than on generic claims.
Mma Triazine H2S Scavengers Market
Trend Two: Chemistry Diversification Accelerates in Response to Supply and Regulation
The precursor disruptions affecting triazine-based scavengers, combined with evolving regulatory expectations around waste, emissions, and handling, will continue to drive interest in alternative chemistries. Nitrogen-free formulations, glycol-derivative-based options, and regenerative systems are likely to gain traction in segments where their performance, safety, or waste profile aligns with operator priorities. This diversification does not imply the obsolescence of established chemistries; triazine-based products remain effective and widely used. Rather, it expands the decision space, giving operators more options to match chemistry to application constraints and risk tolerance. Suppliers that can offer a balanced portfolio, supported by clear guidance on when each chemistry is appropriate, will capture more specification opportunities across a wider range of conditions.
Trend Three: Application Expansion Beyond Traditional Oil and Gas Core
While oil and gas production and gas processing remain the dominant demand centers, adjacent applications in wastewater treatment, industrial effluent handling, and subsea or offshore operations are likely to contribute a growing share of demand. In water treatment, H2S control intersects with odor management, infrastructure protection, and regulatory compliance, creating opportunities for chemistries and delivery methods tailored to aqueous environments. In subsea and offshore settings, the combination of access difficulty, safety criticality, and deposit management creates niche demand for specialized injection and performance assurance approaches. These application expansions do not require a wholesale shift in market structure; they represent incremental growth pockets where focused product development and application expertise can yield disproportionate returns.
Potential risks and uncertainties temper this outlook. Raw material volatility could recur if precursor supply chains remain fragile, affecting pricing and availability for certain chemistries. Regulatory divergence across regions could increase compliance costs and complicate product standardization, particularly for multinational operators managing assets across multiple jurisdictions. Economic cycles in oil and gas investment could influence the pace of new project development and the willingness to adopt newer or more expensive chemistries, even when long-term benefits are clear. Finally, the performance claims surrounding alternative chemistries will need to withstand field validation; products that overpromise on H2S removal, corrosion control, or waste reduction risk reputational damage and specification loss if real-world results fall short.
Strategic Implications for Decision-Makers
For manufacturers and suppliers, the imperative is to build portfolios and capabilities that align with where value is being created. This means investing in application-specific formulation development, expanding evidence-based validation programs, and ensuring that product lines cover both established and emerging chemistry options. Suppliers should also evaluate supply chain resilience, including multi-source sourcing for critical precursors and formulation flexibility that can adapt to raw material constraints. Differentiation will increasingly come from the ability to reduce total treatment cost and risk, not just from the chemistry itself.
For investors, the market offers a profile of steady, regulation-anchored demand with selective pockets of faster growth tied to application expansion and chemistry innovation. The moderate concentration level suggests that market leadership is attainable but not guaranteed, and that success depends on execution in product development, service, and commercial positioning rather than on scale alone. Due diligence should focus on demonstration of field-validated performance, exposure to alternative chemistries and regenerative options, geographic and application diversification, and supply chain robustness. Companies that can show measurable impact on customer revenue, compliance, and operating cost will command stronger competitive positions and more resilient demand.
For procurement and operations leaders, the priority is to move beyond unit price comparisons and evaluate total cost of ownership across dosing efficiency, sludge and waste handling, corrosion impact, handling safety, and compliance documentation. Specification decisions should incorporate application-specific performance data, supplier validation records, and supply reliability considerations, particularly given past precursor disruptions. Where possible, operators should maintain flexibility in chemistry selection, allowing them to adapt to supply conditions, regulatory changes, and evolving operational requirements without compromising H2S control.
The hydrogen sulfide scavengers market is at a point where steady growth, regulatory anchoring, and chemical innovation intersect. Understanding the nuances of product architecture, application economics, and competitive positioning is essential for capturing value in this segment. For those seeking deeper segmentation data, company-level benchmarks, and customized scenario analysis to inform specific investment or procurement decisions, comprehensive market research reports provide the detailed intelligence needed to move from strategic direction to execution.
For detailed analysis of this topic, please visit the official page: Hydrogen Sulfide Scavengers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com